GreenSky Review 2026: Pricing, Pros, Cons, Alternatives
Third-party contract data puts real numbers on GreenSky. The 6 gaps reviewers name, and 5 alternatives that publish a price upfront.
Page at a glance
GreenSky is A bank-funded consumer lending program that lets a contractor close a $10,000-$65,000 residential job on monthly payments, in exchange for a per-transaction merchant fee the contractor absorbs. It publishes no price, so the only way to get a number is to ask a salesperson for one. There is no seat or user licence at all. GreenSky is not sold per user, per tech or per month. The contractor enrolls as a merchant, receives a Merchant Number, and pays only a per-transaction fee on funded loans. GreenSky's own FAQ describes enrollment as a one-page application: "You need to apply to become a GreenSky program merchant. Once enrolled, you are given a Merchant Number. When they submit an application, they will use your Merchant Number." It fits Established residential replacement crews of roughly 5 to 40 people selling one-visit, high-ticket projects at the kitchen table: roof replacements, HVAC system changeouts, window and siding packages, and bath or kitchen remodels where the homeowner's objection is the lump sum rather than the scope. It's the wrong buy for Any contractor operating in Canada, or anywhere outside the United States, because GreenSky's merchant FAQ limits the program to the US without qualification: "Our credit programs are available to home improvement merchants in the United States." Both bank partners are US-chartered institutions. And there's no Canadian offering to negotiate for. Alternatives that publish their prices are Acorn Finance from $0. A quote-only price and what third parties report instead, six evidenced gaps and five alternatives, one of which publish a figure.
The short verdict on GreenSky
GreenSky earns its money with Established residential replacement crews of roughly 5 to 40 people selling one-visit, high-ticket projects at the kitchen table: roof replacements, HVAC system changeouts, window and siding packages, and bath or kitchen remodels where the homeowner's objection is the lump sum rather than the scope. If that's you, it does the job. The sections below are the parts worth checking before you sign. But the fit is narrower than the marketing suggests, and the price isn't the whole cost.
The vendor publishes no price. But every number below was verified on 7 August 2026 and comes from a named third party that says which.
| Pricing model | Custom quote, no published price |
|---|---|
| Entry price | Quote only |
| Users | There is no seat or user licence at all. GreenSky is not sold per user, per tech or per mo |
| Ownership | Sixth Street-led consortium (acquisition completed March 15, 2024) |
| Best fit | Established residential replacement crews of roughly 5 to 40 people selling one-visit, high-ticket projects at the kitchen table: roof replacements, HVAC system changeouts, window and siding packages, and bath or kitchen remodels where the homeowner's objection is the lump sum rather than the scope. |
| Accounting sync | QuickBooks (none), Xero (none), Sage, NetSuite and general ledger systems (none) |
What works
- Ninety seconds to apply, most decisions instant, and no paper accepted at all
- ACH within two business days, but only after the homeowner separately authorizes the draw
- You're funded gross and billed for the fee a month later, which flatters cash flow and hides the cost
- Two separate arbitration agreements with two different opt-out clocks, both waiving class actions
- No self-serve export and no published closure process; the only data route is a privacy request portal
What does not
- The merchant fee moves inversely to how good the offer looks, and it can reach 17.50% of the job
- The CFPB found GreenSky's program let merchants originate loans consumers never authorized, and fined it
- The whole program rests on exactly two banks
- United States only, with no published integration into anything you already run
- The merchant app is thin, breaks on iOS updates, and carries a 3.4 star rating
GreenSky is A bank-funded consumer lending program that lets a contractor close a $10,000-$65,000 residential job on monthly payments, in exchange for a per-transaction merchant fee the contractor absorbs. It sells to HVAC and Remodeling and Roofing and Windows and doors contractors, and the shape of the product follows from that: The homeowner applies from the contractor's phone. The rate sheet describes the flow as "Our fast, paperless application process can take less than 90 seconds. Apply using our mobile app or phone," and reports that "85% of credit decisions are made instantly. Most other credit decisions are made within fifteen minutes." GreenSky's FAQ is emphatic that there's no paper path: "Consumers can submit applications electronically. Paper applications (including fax and email submissions) are not accepted. Applications can be submitted online, through our mobile app, or electronically with the help of a GreenSky Program Customer Service Representative over the phone." And the contractor must verify the homeowner's identity using a government-issued photo ID, and the homeowner supplies name, address, social security number and monthly income.
Ownership matters here more than it usually does. GreenSky is owned by Sixth Street-led consortium (acquisition completed March 15, 2024), so weigh roadmap risk alongside the feature list. An independent product can be bought and folded into somebody else's plan two years after you sign.
The shops GreenSky fits, and the ones it doesn't
It fits Established residential replacement crews of roughly 5 to 40 people selling one-visit, high-ticket projects at the kitchen table: roof replacements, HVAC system changeouts, window and siding packages, and bath or kitchen remodels where the homeowner's objection is the lump sum rather than the scope. That's the half most reviews print. Here's the other half, which is the one worth your time.
Don't buy it if you're Any contractor operating in Canada, or anywhere outside the United States. GreenSky's merchant FAQ limits the program to the US without qualification: "Our credit programs are available to home improvement merchants in the United States." Both bank partners are US-chartered institutions. And there's no Canadian offering to negotiate for. Look at Financeit instead.
Don't buy it if you're Service and repair shops running high-volume, low-ticket work such as HVAC tune-ups, drain clears or single-appliance swaps. The economics don't work at small ticket sizes. A merchant fee that averaged 6.63% across GreenSky's whole book is a tolerable cost on a $18,000 system changeout and a margin-killer on a $600 repair, and the published low-volume penalty of "$35 if funded loan volume is less than $3,500 per month" charges you for enrolling and not using it. Financing is a tool for overcoming a lump-sum objection. And a $600 invoice doesn't create one. Look at Wisetack instead.
Don't buy it if you're Commercial and insurance-restoration contractors billing carriers, property managers or general contractors. GreenSky is a consumer lending program governed by consumer credit law. Every applicant provides "name, address, social security number, and monthly income" and the contractor must verify a government-issued photo ID. And none of that maps to a carrier-funded loss or a commercial AR balance, and GreenSky serves only two verticals, home improvement and healthcare patient financing. Look at A commercial line of credit or invoice factoring facility instead.
Don't buy it if you're A brand-new crew with no closing process and no margin discipline. Financing amplifies whatever sales process you already have. With merchant fees running to 17.50% on the most attractive plans and no published rate card to check against, a shop that can't yet hold a price will hand its entire gross margin to the plan its salespeople like best. So GreenSky is a margin lever for a crew that already sells well, not a substitute for learning to sell. Look at Fix pricing and the close first, then add financing instead.
Pricing: what GreenSky publishes and what it doesn't
There's no published price for GreenSky. The pricing page asks you to get in touch, so every figure below comes from somewhere other than the vendor, and each one says where.
The vendor's own wording is this, and nothing more: "GreenSky confirms in writing that merchants pay a fee on every transaction but refuses to state what the fee is, routing the question to a salesperson instead. There is no pricing page on greensky.com at all: https://www.greensky.com/pricing returns a 312-byte stub reading "Page not found. You are being redirected to https://www.greensky.com/"." So treat every third-party page printing tier names and figures for GreenSky with careful suspicion. Those numbers are not on the vendor's site today, and a roundup that reprints them is telling you what GreenSky used to charge somebody else.
And we aren't going to print a per-month number we can't open a vendor page and read. What exists instead is third-party reporting, dated, from people who saw real contracts. Read it as a range rather than as a quote you can hold anyone to.
| Reported range | Reported on | Source |
|---|---|---|
| 0.50% to 17.50% merchant fee per funded transaction | 2020-09-01 | A GreenSky Program Rate Sheet published by EGIA (a contractor trade association and financing clearinghouse) lists the actual per-plan merchant fee for 25 credit plans. The fees run from 0.50% on the "Reduced Rate 9.99% Standard" plan (#2740) to 17.50% on both the 60-month 0% interest plan (#6160) and the 12-month 0% APR & No Payments promotional plan (#1125). Mid-range examples: 6-Month No Interest No Pay is 4.55%, 24-Month No Interest w/Pmts is 11.75%, 36-month 0% interest is 14.25%, 48-month 0% interest is 15.75%. The pattern is unambiguous and it is the single most important fact about GreenSky's economics: the cheaper the payment plan looks to the homeowner, the more the contractor pays. Figures confirmed against the PDF's embedded text layer, not just the rendered page. |
| 6.63% average transaction fee rate across all merchants | 2021-07-28 | GreenSky's own quarterly earnings release, from the period when it was a public company, discloses the blended rate it actually collected across its whole merchant base: "The average transaction fee rate increased 2 bps to 6.63%." The same release states "Second quarter transaction volume was $1.5 billion, an increase of 14% when compared to the second quarter of 2020." A contractor can treat 6.63% as the realistic planning midpoint rather than the 0.50% floor on the rate sheet. |
| $35 per month when funded loan volume is under $3,500; ACH return fee the greater of $30 or 5% | 2020-09-01 | The same EGIA rate sheet discloses two merchant-side penalty fees in its fine print, which no page on greensky.com mentions: "ACH Return Fee/Late Fee in the amount of the greater of $30 or 5% of the payment amount on all returned merchant fee ACHs and a $35 fee if funded loan volume is less than $3,500 per month." The $35 charge is a low-volume penalty, so a contractor who enrolls and then funds little or nothing pays to stay enrolled. |
There is no seat or user licence at all. GreenSky is not sold per user, per tech or per month. The contractor enrolls as a merchant, receives a Merchant Number, and pays only a per-transaction fee on funded loans. GreenSky's own FAQ describes enrollment as a one-page application: "You need to apply to become a GreenSky program merchant. Once enrolled, you are given a Merchant Number. When they submit an application, they will use your Merchant Number."
The GreenSky line items nobody mentions on the demo
Payment processing. The merchant fee is the payment processing cost, and it is deducted through monthly invoicing rather than netted out of each funding. GreenSky states: "We invoice participating merchants each month for any transaction that occurred the previous month." The contractor therefore receives the full loan amount by ACH within two business days and pays the fee back later, which flatters early cash flow and creates a lumpy monthly bill. The EGIA rate sheet confirms the merchant fee is collected by ACH debit, since it specifies a return fee "on all returned merchant fee ACHs".
Implementation and onboarding. There is no implementation project and no onboarding fee is disclosed anywhere. GreenSky describes enrollment as completing and submitting "our one-page application", after which the merchant receives a Merchant Number and can transact. The EGIA rate sheet describes the operating loop as a three-step process: apply for credit in under 90 seconds by mobile app or phone, get approved ("85% of credit decisions are made instantly"), then get funded by submitting a Transaction Request in the Merchant Portal.
Minimum term. Ask for the Merchant Agreement before signing and get the term, termination-for-convenience notice period, and any exclusivity or minimum-volume commitment in writing. The merchant agreement isn't published anywhere on greensky.com; only the consumer-facing Program Arbitration Agreement and the website Terms of Use are public. And ask specifically whether the $35 low-volume fee on the EGIA rate sheet applies to your program, since it's the only recurring charge anyone has published.
Getting out. Ask what happens to loans already funded and to merchant fees already invoiced if you leave the program, and whether GreenSky can offset unpaid merchant fees against pending fundings. And ask whether chargeback or buyback obligations survive termination when a homeowner disputes a job.
Auto-renewal. Ask whether the Merchant Agreement auto-renews and whether GreenSky can change the merchant fee schedule unilaterally mid-term. And the published EGIA rate sheet carried an expiry on its best plans ("Special Promotional Programs for EGIA Only Through March 31st 2021"), which shows the fee table is a moving target rather than a fixed contractual rate.
Modules sold separately. We found none. The published feature set appears to sit inside the tiers rather than behind separate line items, which is worth confirming against your own must-have list on the call.
"Third-party reporting puts GreenSky at 0.50% to 17.50% merchant fee per funded transaction, reported 2020-09-01."
A GreenSky Program Rate Sheet published by EGIA (a contractor trade association and financing clearinghouse) lists the actual per-plan merchant fee for 25 credit plans. The fees run from 0.50% on the "Reduced Rate 9.99% Standard" plan (#2740) to 17.50% on both the 60-month 0% interest plan (#6160) and the 12-month 0% APR & No Payments promotional plan (#1125). Mid-range examples: 6-Month No Interest No Pay is 4.55%, 24-Month No Interest w/Pmts is 11.75%, 36-month 0% interest is 14.25%, 48-month 0% interest is 15.75%. The pattern is unambiguous and it is the single most important fact about GreenSky's economics: the cheaper the payment plan looks to the homeowner, the more the contractor pays. Figures confirmed against the PDF's embedded text layer, not just the rendered page. (9-01)
One oddity, filed under things nobody mentions on a demo. GreenSky's merchant fee moves inversely to the attractiveness of the consumer offer, so the plan your closer most wants to present is the one that costs you most. And the published spread runs from 0.50% on a plain 9.99% reduced-rate plan to 17.50% on a 60-month 0% interest plan, a 35-fold difference on the same funded dollar. Plan selection is a pricing decision disguised as a sales decision, and most shops delegate it to whoever is standing in the kitchen. On a $20,000 job the difference between the cheapest and dearest plan is about $3,400 of gross margin. So decide centrally which plans may be offered, put the fee next to each plan on the sales sheet, and require approval to go past a threshold.
What a GreenSky quote leaves out
The subscription is the part everyone quotes. These are the lines that land afterwards, and the ones we could not find are named as unpublished rather than left blank.
Sold separately. We found none. The published feature set sits inside the tiers rather than behind separate line items, which is worth confirming against your own must-have list.
"GreenSky answers the question of what it costs with this and nothing else: "GreenSky confirms in writing that merchants pay a fee on every transaction but refuses to state what the fee is, routing the question to a salesperson instead. There is no pricing page on greensky.com at all: https://www.greensky.com/pricing returns a 312-byte stub reading "Page not found. You are being redirected to https://www.greensky.com/".""
GreenSky pricing page (2026)
"There is no seat or user licence at all. GreenSky is not sold per user, per tech or per month. The contractor enrolls as a merchant, receives a Merchant Number, and pays only a per-transaction fee on funded loans. GreenSky's own FAQ describes enrollment as a one-page application: "You need to apply to become a GreenSky program merchant. Once enrolled, you are given a Merchant Number. When they submit an application, they will use your Merchant Number.""
GreenSky pricing page (2026)
"GreenSky is reported at 0.50% to 17.50% merchant fee per funded transaction as of 2020-09-01."
A GreenSky Program Rate Sheet published by EGIA (a contractor trade association and financing clearinghouse) lists the actual per-plan merchant fee for 25 credit plans. The fees run from 0.50% on the "Reduced Rate 9.99% Standard" plan (#2740) to 17.50% on both the 60-month 0% interest plan (#6160) and the 12-month 0% APR & No Payments promotional plan (#1125). Mid-range examples: 6-Month No Interest No Pay is 4.55%, 24-Month No Interest w/Pmts is 11.75%, 36-month 0% interest is 14.25%, 48-month 0% interest is 15.75%. The pattern is unambiguous and it is the single most important fact about GreenSky's economics: the cheaper the payment plan looks to the homeowner, the more the contractor pays. Figures confirmed against the PDF's embedded text layer, not just the rendered page. (9-01)
The five workflows you pay for
Feature totals are noise. So a shop in this category lives or dies on five things, and those are the five to grade, and each one below carries the evidence it's graded on.
Ninety seconds to apply, most decisions instant, and no paper accepted at all The homeowner applies from the contractor's phone. The rate sheet describes the flow as "Our fast, paperless application process can take less than 90 seconds. Apply using our mobile app or phone," and reports that "85% of credit decisions are made instantly. Most other credit decisions are made within fifteen minutes." GreenSky's FAQ is emphatic that there's no paper path: "Consumers can submit applications electronically. Paper applications (including fax and email submissions) are not accepted. Applications can be submitted online, through our mobile app, or electronically with the help of a GreenSky Program Customer Service Representative over the phone." And the contractor must verify the homeowner's identity using a government-issued photo ID, and the homeowner supplies name, address, social security number and monthly income.
ACH within two business days, but only after the homeowner separately authorizes the draw Approval doesn't release money. The homeowner receives a text or email and must approve the transaction before the contractor is paid: "Your Customer will receive a text message or email to approve the transaction. When your Customer grants authorization, payments will be received within two business days." Same-day payment is possible "provided your customer has authorized the transaction." For staged work the Merchant Portal handles progress draws: "Use the GreenSky Merchant Portal to process progress payments up to your staged funding limit. When the project is complete you will process payment in the exact same way." And that second authorization step is the control the CFPB order required GreenSky to strengthen, and it's why a contractor can't fund a job the homeowner has gone quiet on.
You're funded gross and billed for the fee a month later, which flatters cash flow and hides the cost GreenSky doesn't net its fee out of the funding. It states: "We invoice participating merchants each month for any transaction that occurred the previous month." The contractor therefore sees the full loan amount hit the bank account and pays the merchant fee back on a lagging monthly invoice collected by ACH debit, which the EGIA rate sheet confirms by specifying a return fee "on all returned merchant fee ACHs." So the practical effect is that the true cost of a financed job never appears on the job's own P&L unless somebody deliberately allocates it back, and a busy month produces a merchant fee invoice that arrives after the money has been spent.
Two separate arbitration agreements with two different opt-out clocks, both waiving class actions GreenSky runs two distinct arbitration regimes and they don't share a deadline. The website Terms of Use contain "MANDATORY BINDING ARBITRATION AND A CLASS ACTION WAIVER" administered by JAMS, with exclusive venue in "the state or federal courts located in the applicable county within the State of Georgia," and give a 30-day window: "you must notify GS in writing no later than 30 days after first becoming subject to this Arbitration Agreement." The separate GreenSky Program Arbitration Agreement, last updated April 27, 2026, governs loan applicants and gives 45 days: "YOUR REJECTION NOTICE MUST BE RECEIVED WITHIN 45 DAYS AFTER THE DATE YOU SUBMIT YOUR APPLICATION." It exempts service members protected by the Military Lending Act. Both forbid class actions. Yet neither is the Merchant Agreement, which GreenSky doesn't publish at all.
No self-serve export and no published closure process; the only data route is a privacy request portal Nothing on greensky.com describes exporting your funded-loan history, your customer list or your merchant fee statements, and nothing describes how a merchant closes an account. The only structured data mechanism the site exposes is a OneTrust privacy request form reached from the footer's California Privacy link, which is a consumer data-subject access route rather than a merchant export. So practically, a contractor's financing history lives inside the Merchant Portal and leaves only as whatever the portal happens to let you print.
How GreenSky lands by trade
Fit differs by trade rather than by company size alone, and a blended paragraph hides that. Here is the split for the trades this one sells to.
HVAC. The workflow that decides it is ninety seconds to apply, most decisions instant, and no paper accepted at all, and the shop profile that gets value is residential replacement crews of 5 to 40 doing $10k+ single-visit tickets in the us doing residential work. Where it stops being a fit is Any contractor operating in Canada, or anywhere outside the United States.
Remodeling. The workflow that decides it is ninety seconds to apply, most decisions instant, and no paper accepted at all, and the shop profile that gets value is residential replacement crews of 5 to 40 doing $10k+ single-visit tickets in the us doing residential work. Where it stops being a fit is Any contractor operating in Canada, or anywhere outside the United States.
Roofing. The workflow that decides it is ninety seconds to apply, most decisions instant, and no paper accepted at all, and the shop profile that gets value is residential replacement crews of 5 to 40 doing $10k+ single-visit tickets in the us doing residential work. Where it stops being a fit is Any contractor operating in Canada, or anywhere outside the United States.
Windows and doors. The workflow that decides it is ninety seconds to apply, most decisions instant, and no paper accepted at all, and the shop profile that gets value is residential replacement crews of 5 to 40 doing $10k+ single-visit tickets in the us doing residential work. Where it stops being a fit is Any contractor operating in Canada, or anywhere outside the United States.
The GreenSky accounting link, and where it stops
QuickBooks connects, on every plan. Xero connects, on every plan. Sage, NetSuite and general ledger systems connects, on every plan. Your costs map through cost codes, so test yours against your own chart of accounts before you commit. A code your books don't recognise is how a labour charge quietly lands somewhere useless.
Past those, the road ends. Any CRM or field service management platform (Jobber, Housecall Pro, ServiceTitan, AccuLynx, Buildertrend), Google Play (Android merchant app), Zapier or any general automation layer do not connect. So if your books run on an ERP rather than the platforms named above, weigh that before anything else.
Beyond accounting it connects to Pinnacle Bank, a Tennessee bank, dba Synovus Bank (Program lender. One of exactly two financial institutions currently making loans through the GreenSky Program. NMLS# 418535.), Comenity Capital Bank, a Utah state-chartered bank, Member FDIC (Program lender. The second and final institution listed on the bank-partners page. NMLS# 694363.), EGIA (Electric & Gas Industries Association) (Trade association acting as a financing clearinghouse, reselling the GreenSky Program to member contractors under a negotiated plan table.), GreenSky Merchant mobile app (iOS) (The point-of-sale application tool. Free, published by GreenSky Trade Credit, LLC, version 9.9.1 as of July 30, 2026, requiring iOS 15.0 or later.). A public API exists: No public API, no developer portal and no integration documentation of any kind is published. GreenSky describes itself as licensing "a technology platform and certain program names" to its partner banks, not to merchants. All merchant activity runs through the Merchant Portal at portal.greensky.com or the mobile app.
What happens when GreenSky breaks
Support is the line item nobody prices and everybody eventually needs. Onboarding for GreenSky: There is no implementation project and no onboarding fee is disclosed anywhere. GreenSky describes enrollment as completing and submitting "our one-page application", after which the merchant receives a Merchant Number and can transact. The EGIA rate sheet describes the operating loop as a three-step process: apply for credit in under 90 seconds by mobile app or phone, get approved ("85% of credit decisions are made instantly"), then get funded by submitting a Transaction Request in the Merchant Portal.
And a sales rep at a home improvement merchant, describes it the same thing: "This company has helped increase my Sales huge! Great customer service 7 days a week. Always able to contact a representative without a 10 minute hold on the phone. Polite, courteous and informative. Also, this app is very easy to use!"
The GreenSky term, and what leaving costs
Nobody reads this section before they buy, and it's the one that costs money afterwards. Four terms decide what leaving looks like.
Minimum term. Ask for the Merchant Agreement before signing and get the term, termination-for-convenience notice period, and any exclusivity or minimum-volume commitment in writing. The merchant agreement isn't published anywhere on greensky.com; only the consumer-facing Program Arbitration Agreement and the website Terms of Use are public. And ask specifically whether the $35 low-volume fee on the EGIA rate sheet applies to your program, since it's the only recurring charge anyone has published.
Auto-renewal. Ask whether the Merchant Agreement auto-renews and whether GreenSky can change the merchant fee schedule unilaterally mid-term. And the published EGIA rate sheet carried an expiry on its best plans ("Special Promotional Programs for EGIA Only Through March 31st 2021"), which shows the fee table is a moving target rather than a fixed contractual rate.
Early termination. Ask what happens to loans already funded and to merchant fees already invoiced if you leave the program, and whether GreenSky can offset unpaid merchant fees against pending fundings. And ask whether chargeback or buyback obligations survive termination when a homeowner disputes a job.
Payment processing. The merchant fee is the payment processing cost, and it is deducted through monthly invoicing rather than netted out of each funding. GreenSky states: "We invoice participating merchants each month for any transaction that occurred the previous month." The contractor therefore receives the full loan amount by ACH within two business days and pays the fee back later, which flatters early cash flow and creates a lumpy monthly bill. The EGIA rate sheet confirms the merchant fee is collected by ACH debit, since it specifies a return fee "on all returned merchant fee ACHs".
Worth a detour here. GreenSky publishes zero integrations, zero API documentation and no data export path, which is remarkable for a system that holds a contractor's entire financed-revenue history. The only structured data mechanism on the site is a consumer privacy request form. Every financed job you close leaves an audit trail that lives only in someone else's portal, and you have no published route to get it out in bulk. So export or print your funded-loan and merchant-fee statements monthly as a matter of routine, and reconcile them against your own books rather than trusting the portal to be there when you need history for a dispute.
"GreenSky is reported at 6.63% average transaction fee rate across all merchants as of 2021-07-28."
GreenSky's own quarterly earnings release, from the period when it was a public company, discloses the blended rate it actually collected across its whole merchant base: "The average transaction fee rate increased 2 bps to 6.63%." The same release states "Second quarter transaction volume was $1.5 billion, an increase of 14% when compared to the second quarter of 2020." A contractor can treat 6.63% as the realistic planning midpoint rather than the 0.50% floor on the rate sheet. (7-28)
"We were a roofing contractor company looking for a way to offer financing to our customers. After some digging we came upon greensky and their sales rep Lindsey Myers. From the beginning the professionalism and competence demonstrated by Ms. Myers was second to none. Her attitude was pleasant and cheerful throughout the entire process even when we had to reschedule last minute.. She was very accommodating and understanding of our work days as contractors. She even stayed late, after 630pm to accommodate our schedule. With customer service like Lindsey's, there's no doubt Greensky will continue to flourish."
Apple App Store (GreenSky Merchant), monty5427 (2026)
"This company has helped increase my Sales huge! Great customer service 7 days a week. Always able to contact a representative without a 10 minute hold on the phone. Polite, courteous and informative. Also, this app is very easy to use!"
Apple App Store (GreenSky Merchant), Montana Renewal Rep (2026)
The GreenSky gaps worth raising on the call
So here's what breaks, sourced to the person who hit it.
The merchant fee moves inversely to how good the offer looks, and it can reach 17.50% of the job This is the central economic fact and GreenSky won't state it on its website. On the EGIA rate sheet the plans a salesperson most wants to present are the most expensive to present. A 60-month 0% interest plan costs the contractor a 17.50% merchant fee, a 48-month 0% plan costs 15.75%, and a 36-month 0% plan costs 14.25%, while the plain "Reduced Rate 9.99% Standard" plan costs 0.50%. So on a $20,000 roof, choosing the 60-month 0% plan instead of the standard reduced-rate plan moves $3,400 of gross margin from the contractor to GreenSky. A crew that lets salespeople pick the plan by what closes fastest, rather than by what it costs, will quietly finance its own discount. Before you enroll, ask for the full plan table with the merchant fee next to every plan number, then set a written rule about which plans your salespeople may present without a manager's approval. And price the fee into the job the way you price material, not as an afterthought.
The CFPB found GreenSky's program let merchants originate loans consumers never authorized, and fined it On July 12, 2021 the Bureau issued a consent order finding that GreenSky "engaged in origination activity on thousands of loans to consumers who did not request or authorize them and that the company structured its loan origination and servicing program in a manner that enabled the origination of unauthorized loans." The order required GreenSky to refund or cancel loans up to $9 million, implement enhanced authorization and verification procedures, and pay a $2.5 million civil penalty. The Bureau's own press release is titled "CFPB Takes Action Against Fintech Company GreenSky for Enabling Merchants to Secure Loans for Consumers Without Their Authorization." The merchant in that sentence is the contractor. So a contractor whose salespeople run applications loosely is operating inside a program that has already been penalised for exactly that failure mode, and the homeowner's complaint will name the contractor first. Write a hard rule that no application is submitted without the homeowner physically present and holding their own government-issued ID, and keep the text or email authorization record with the job file. And GreenSky's own funding step requires customer confirmation by text, email or phone, so the audit trail exists. Use it.
The whole program rests on exactly two banks GreenSky's bank-partners page lists precisely two financial institutions currently making loans through the program: Pinnacle Bank, a Tennessee bank, dba Synovus Bank (NMLS# 418535), and Comenity Capital Bank, a Utah state-chartered bank, Member FDIC (NMLS# 694363). GreenSky repeatedly stresses that it isn't the lender: "GreenSky, LLC and GreenSky Servicing, LLC are not lenders. All credit decisions and loan terms are determined by program lenders." If either bank tightens its credit box or exits, a contractor who has built a whole sales process around one financing offer has no second rail. And approval rates and available plans are set by parties the contractor has no relationship with. Carry a second financing source from day one so a declined homeowner still has a path. And ask your rep what happened to approval rates the last time a bank partner changed, and check the bank-partners page again at renewal.
United States only, with no published integration into anything you already run GreenSky states plainly that "Our credit programs are available to home improvement merchants in the United States." So there's no Canadian program. Separately, and unusually for a tool in a contractor's stack, greensky.com publishes no integrations directory, no partner list, no developer documentation and no API reference anywhere across its home, who-we-serve, home-improvement, merchant FAQ, disclosures or terms pages. Financing activity lives in the Merchant Portal and the mobile app, and it doesn't flow into a CRM or an accounting ledger by any published route. If you're Canadian, stop here and look at a domestic lender. And if you're in the US, plan for manual reconciliation between funded loans and your accounting system, and ask the rep directly whether any file export or API exists, because nothing is published.
The merchant app is thin, breaks on iOS updates, and carries a 3.4 star rating The GreenSky Merchant app sits at 3.38 stars across 115 ratings on the US App Store. Reviewers report the application flow failing at specific steps: one merchant cannot get past the address field after an iPhone update, another finds that after submitting loan information there is no way to input anything further and that screen orientation doesn't change on iOS the way it does on Android. A separate reviewer asks for typed plan entry to replace a dropdown, which matters when a salesperson is picking among 25 plan numbers on a kitchen table. But note the honest caveat: a large share of the app's low ratings come from homeowners who downloaded a merchant-only app by mistake and complain about a PIN they were never issued, so the rating understates the merchant experience. A merchant using both ios and android writes: "After submitting loan information and tapping continue, there's no way to input anything into the system. Orientation doesn't change in iOS and this is how I work around this issue in the Android app. Please help. Thanks" Have your closers test the full application flow on their own phones and OS versions before you build a pitch around it, and keep the Merchant Portal open on a laptop as a fallback. And don't let a $20,000 close depend on an app step that fails after an iOS update.
Deferred interest plans hand the homeowner a 17.99% to 26.99% rate if they miss the payoff window The "No Interest if Paid in Full" plans are deferred interest, not waived interest. The rate sheet states that "For deferred interest plans, interest accrues during the promotional period but all interest is waived if the purchase amount is paid in full before the end of the promotional period," and the interest rate column on every one of those plans reads 17.99%-26.99%. A homeowner who is one payment short on the final day owes the entire accrued balance at that rate. GreenSky's marketing to contractors leads with "We have rates as low as 0%." Both statements are true and they describe the same product. And the angry phone call lands with the contractor who sold it. Train your salespeople to say the words "deferred interest" and to state the payoff date out loud, and put the promotional end date on the customer's copy of the paperwork. It costs you nothing. And it removes the single most common financing complaint.
One more thing worth knowing. The only published GreenSky fee schedule contains a low-volume penalty that appears nowhere on greensky.com: a $35 charge in any month your funded loan volume falls under $3,500. Enrolling and not using the program has a running cost. Contractors routinely sign up for financing programs as an option to have on the shelf. But this one bills you for shelf space, and it bills through an ACH debit that carries its own return penalty. Ask explicitly whether a minimum-volume fee applies to your program before you enrol, and if you're a seasonal trade, ask what happens in your slow quarter.
One more thing worth knowing. GreenSky advertises a 4.9 star Google rating to contractors in its site footer, but that badge measures borrowers rating the loan servicer. The tool contractors hold in their hands, the GreenSky Merchant app, sits at 3.38 stars, and the merchant-side complaints cluster on the application flow breaking mid-submission. Don't read the 4.9 badge as evidence about the merchant experience, because the two ratings measure different products and different populations. Have your closers install the app and run a dummy application on their own phones and OS versions before you build a sales process on it. But in fairness, part of the 3.38 is dragged down by homeowners who installed a merchant-only app by mistake, so the merchant reality is somewhat better than the number implies.
One more thing worth knowing. The entire program rests on exactly two banks, and GreenSky goes out of its way to make clear it controls none of the lending decisions a contractor's close rate depends on. Your approval rate is set by two balance sheets you have no relationship with, and if either tightens its credit box your close rate moves without warning and without anyone telling you why. So carry a second financing source so a decline has somewhere to go, and re-check the bank-partners page at every renewal.
Small thing that turns out to matter. GreenSky's own published rate sheet contradicts itself inside a single footnote about split tickets, stating both that they're forbidden and that they're allowed. Splitting a job across two credit plans or two applications is a normal contractor instinct on a large or phased project, and the one document that addresses it gives opposite answers. So get a written answer from your rep on whether you may split a ticket, because the ambiguity sits on the side of the party that can claw back a funding, not on yours.
The GreenSky review corpus, read by complaint
Every quote below is transcribed from a published review, named to the platform that carries it and to the reviewer as that platform displays them. We read the corpus by complaint type rather than by star rating, which is how the disqualifying detail buried inside a five-star review gets found.
"We were a roofing contractor company looking for a way to offer financing to our customers. After some digging we came upon greensky and their sales rep Lindsey Myers. From the beginning the professionalism and competence demonstrated by Ms. Myers was second to none. Her attitude was pleasant and cheerful throughout the entire process even when we had to reschedule last minute.. She was very accommodating and understanding of our work days as contractors. She even stayed late, after 630pm to accommodate our schedule. With customer service like Lindsey's, there's no doubt Greensky will continue to flourish."
A roofing contractor / merchant says on Apple App Store (GreenSky Merchant)
"This company has helped increase my Sales huge! Great customer service 7 days a week. Always able to contact a representative without a 10 minute hold on the phone. Polite, courteous and informative. Also, this app is very easy to use!"
A sales rep at a home improvement merchant, says on Apple App Store (GreenSky Merchant)
"The app works great and the customer service is excellent. Green Sky makes me money."
A merchant, describes it on Apple App Store (GreenSky Merchant)
"I'm giving this three stars because the reality of this app is that it's for merchants only and aside from the name (which I guess should be a clue) it's not really well defined. I was advised to download the app to manage my loan by someone who help me set up the loan only to end up confused as to why I downloaded an app I literally cannot use as it is, in fact, for merchants only. GreenSky, you should change the name of the app to say "merchant ONLY" or, offer the app on a merchant specific section of your website ONLY. Don't have it posted in the AppStore for the general public to even see."
A homeowner / borrower who downloaded the merchant app by mistake, puts it on Apple App Store (GreenSky Merchant)
"After submitting loan information and tapping continue, there's no way to input anything into the system. Orientation doesn't change in iOS and this is how I work around this issue in the Android app. Please help. Thanks"
But a merchant using both ios and android, puts it it differently on Apple App Store (GreenSky Merchant)
"With the new iPhone update I can't get past the address step on an application. Please help and get it up to standard"
But a merchant, reports it it differently on Apple App Store (GreenSky Merchant)
"Please revert back to entering plans by typing instead of drop down."
But a merchant, puts it it differently on Apple App Store (GreenSky Merchant)
"Fix the bugs, please or get rid of it altogether"
A reviewer, reports it on Apple App Store (GreenSky Merchant)
"I don't trust the monthly bill they are sending me. The data is always behind. Not all my payments are on it. When I try to chat through the app. The app keeps having to re-generate the connection and the live body that I am chatting with logs off before the connection starts again. The email they sent is missing one payment and shows interest deducted from my payment. The people on the phone are double talking. I want is the true amount due. But am I getting that or am I getting the gross amount plus the potential interest?"
A borrower disputing statement accuracy describes it on Apple App Store (GreenSky Merchant)
GreenSky and the alternatives, side by side
Four or five real options, each with what it does better and what it does worse. Both halves, or it's marketing.
| Tool | Entry price | Billing unit | Users included | Published? |
|---|---|---|---|---|
| GreenSky | Quote only | Custom quote | There is no seat or user licence at all. GreenSky is not sol | No |
| Acorn Finance | $0 | per transaction (dealer fee) | Unlimited; no seat licence | Yes |
| Wisetack | Quote only | per transaction (merchant fee) | Unlimited; no seat licence | No |
| Hearth | Quote only | per account (subscription) | Not published | No |
| Service Finance Company, LLC | Quote only | per transaction (dealer fee) | Unlimited; no seat licence | No |
| Financeit | Quote only | per transaction (merchant fee) | Unlimited; no seat licence | No |
Acorn Finance. Publishing its merchant-side cost in plain language. Acorn states "Contractors get a financing platform with no dealer fees," which is the exact disclosure GreenSky declines to make. And it runs a multi-lender marketplace, so one soft pull returns competing offers instead of a single bank's answer. But Depth of the home improvement program. GreenSky carries staged funding limits for progress draws on long projects and credit limits up to $100,000, and its two-bank structure produces the deep 0% promotional plans a replacement-window or roofing closer expects to present.
Wisetack. Transparency on the consumer side and fit for smaller tickets. Wisetack publishes its full consumer range: "Offers range from 0 to 35.9% APR based on amount requested and creditworthiness," with "No prepaid finance charges or participation fees" and terms from 3 to 120 months. And it's built for service work as well as projects. But Ticket ceiling and merchant fee disclosure. Wisetack tops out around $65K against GreenSky's $100,000 credit limits, and like GreenSky it routes merchant pricing to "TALK TO SALES" rather than publishing a rate card.
Hearth. Bundling financing with contractor sales tooling such as quotes, invoicing and payments, so financing isn't a separate silo the way the GreenSky Merchant Portal is. But Cost transparency. No price appears in the raw HTML of hearth.com's homepage, and there's no reachable pricing page, so a buyer is quoting blind on both the subscription and the financing economics.
Service Finance Company, LLC. Bank ownership and balance-sheet stability. Service Finance is a Truist company, so the lender and the program administrator are the same institution rather than a fintech intermediating two unrelated banks. But Mobile tooling. Its dealer app is rated 2.05 stars across 130 ratings on the US App Store, materially below GreenSky Merchant's 3.38 across 115, and its merchant pricing is equally unpublished.
Financeit. Serving Canada, which GreenSky doesn't do at all. And for any contractor north of the border this is the difference between a usable program and no program. But US scale and plan depth. GreenSky reported $1.5 billion of transaction volume in a single quarter across a nationwide merchant network, and no comparable published volume disclosure supports a like-for-like comparison.
"The app works great and the customer service is excellent. Green Sky makes me money."
Apple App Store (GreenSky Merchant), Rocket marc (2026)
"I'm giving this three stars because the reality of this app is that it's for merchants only and aside from the name (which I guess should be a clue) it's not really well defined. I was advised to download the app to manage my loan by someone who help me set up the loan only to end up confused as to why I downloaded an app I literally cannot use as it is, in fact, for merchants only. GreenSky, you should change the name of the app to say "merchant ONLY" or, offer the app on a merchant specific section of your website ONLY. Don't have it posted in the AppStore for the general public to even see."
Apple App Store (GreenSky Merchant), Hakaibutsu (2026)
Who should not buy GreenSky
Don't buy GreenSky if you're Any contractor operating in Canada, or anywhere outside the United States. GreenSky's merchant FAQ limits the program to the US without qualification: "Our credit programs are available to home improvement merchants in the United States." Both bank partners are US-chartered institutions. And there's no Canadian offering to negotiate for. Look at Financeit instead.
Don't buy GreenSky if you're Service and repair shops running high-volume, low-ticket work such as HVAC tune-ups, drain clears or single-appliance swaps. The economics don't work at small ticket sizes. A merchant fee that averaged 6.63% across GreenSky's whole book is a tolerable cost on a $18,000 system changeout and a margin-killer on a $600 repair, and the published low-volume penalty of "$35 if funded loan volume is less than $3,500 per month" charges you for enrolling and not using it. Financing is a tool for overcoming a lump-sum objection. And a $600 invoice doesn't create one. Look at Wisetack instead.
Don't buy GreenSky if you're Commercial and insurance-restoration contractors billing carriers, property managers or general contractors. GreenSky is a consumer lending program governed by consumer credit law. Every applicant provides "name, address, social security number, and monthly income" and the contractor must verify a government-issued photo ID. And none of that maps to a carrier-funded loss or a commercial AR balance, and GreenSky serves only two verticals, home improvement and healthcare patient financing. Look at A commercial line of credit or invoice factoring facility instead.
Don't buy GreenSky if you're A brand-new crew with no closing process and no margin discipline. Financing amplifies whatever sales process you already have. With merchant fees running to 17.50% on the most attractive plans and no published rate card to check against, a shop that can't yet hold a price will hand its entire gross margin to the plan its salespeople like best. So GreenSky is a margin lever for a crew that already sells well, not a substitute for learning to sell. Look at Fix pricing and the close first, then add financing instead.
The verdict, by shop size
Residential replacement crews of 5 to 40 doing $10K+ single-visit tickets in the US
Yes, and this is the shape the product is built for. This is the profile the program was built for and it works. Sub-90-second applications with 85% instant decisions, credit limits to $100,000, staged funding for progress draws, and ACH funding within two business days of the homeowner's authorization all fit a kitchen-table close on a roof, a system changeout or a window package. The condition is that you treat the merchant fee as a cost of goods. Get the full plan table with fees attached, decide centrally which plans your closers may present, and price accordingly. A contractor who does that captures the close-rate lift. But one who lets salespeople reach for the 60-month 0% plan because it sounds best gives 17.50% of the job back. This band runs 5 to 40 on the crew, doing residential work, and that's the profile the recommendation is written for.
Large multi-branch residential operations above roughly 40 field staff
Only under conditions, and they are worth being honest about. The volume justifies the program, and at this scale you have real negotiating leverage on the fee schedule, so the published 0.50% to 17.50% range should be treated as an opening position rather than a rate card. But the conditions are structural. GreenSky publishes zero integrations and no API, so financing data won't reach your CRM or your general ledger without manual work, and that manual reconciliation gets expensive across branches. The program also rests on two banks, which is a real concentration risk for an operation that can't afford an approval-rate shock. Negotiate the fee table hard, run a second financing source in parallel, and budget for the reconciliation labour. This band runs 40 or more on the crew, doing residential work, and that's the profile the recommendation is written for.
Service, repair and maintenance shops on sub-$2,000 average tickets
No. The maths doesn't work and the fee structure punishes you for trying. A blended merchant fee that GreenSky itself reported at 6.63% is survivable on a $18,000 project and destroys margin on a $600 repair, and the only recurring charge anyone has published is a penalty for not transacting: "$35 if funded loan volume is less than $3,500 per month." And small tickets don't generate the lump-sum objection financing exists to solve. Use a lighter, service-oriented option and keep your repair margin. This band runs 1 or more on the crew, doing service work, and that's the profile the recommendation is written for.
Commercial, insurance restoration and any contractor outside the United States
No. GreenSky is structurally unavailable or inapplicable. The program is limited to "home improvement merchants in the United States," so Canadian and other non-US contractors can't enrol at all. And for commercial and insurance work the product is the wrong instrument regardless of geography: every application requires a consumer's social security number, monthly income and a verified government photo ID, which describes a homeowner and not a carrier, a property manager or a general contractor's AR balance. This band runs 1 or more on the crew, doing commercial and insurance work, and that's the profile the recommendation is written for.
Where we come into the GreenSky question
We should declare an interest, or rather the absence of one. Fervor takes nothing from GreenSky or any of its rivals. What we've got is data on the demand side.
GreenSky charges the contractor a per-transaction merchant fee that reached 17.50% on its most attractive plans and averaged 6.63% across its whole book, which means every financed job already carries a double-digit acquisition-side cost before a single dollar of advertising. So that makes the free half of the funnel unusually valuable, and it's the half most contractors leave broken: Fervor inspected the contractor sites in its index and found 95.8% carry a serious WCAG violation and 61.3% a critical one. A homeowner using a screen reader, or simply tabbing through a quote form with a keyboard, is a homeowner who never reaches the kitchen table where the GreenSky app gets opened.
So we went and looked. We inspected 380 contractor websites for the Contractor CRO Index, and 95.8% of them carried a serious accessibility violation. So the sample is not curated: it is every contractor site the tooling could reach. The full write-up is in the Contractor CRO Index.
"95.8% of the 380 contractor websites inspected carried a serious accessibility violation."
Fervor Studio Contractor CRO Index (2026)
And none of that argues against the purchase. It argues for checking the cheaper problem first. The numbers are all public.
See where your site is losing the jobs GreenSky would have managed
Fervor inspects your site the way a homeowner uses it, then shows you where calls leak out. About three days.
Get a Site InspectionHow this GreenSky page was researched
We didn't run GreenSky on a live job, and we won't imply otherwise. So here's the basis. We read 12 vendor pages for GreenSky on 7 August 2026, and we went through the reviews looking for complaints rather than for averages. Prices were checked the same day. Nothing here is carried forward from an older sweep.
So: nine quotes on this page, nine from Apple App Store (GreenSky Merchant).
And Trustpilot (https://www.trustpilot.com/review/greensky.com) — HTTP 403 to both curl and WebFetch, Capterra (https://www.capterra.com/p/187423/GreenSky/) — HTTP 403, BBB (https://www.bbb.org/us/ga/atlanta/profile/financial-services/greensky-llc-0443-27505628) — HTTP 403 and GreenSky merchant enrolment form (https://merchant-enrollment.greensky.com/) — HTTP 403, so published eligibility criteria such as minimum years in business or minimum revenue couldn't be verified and are deliberately not recorded refused automated retrieval for GreenSky. Where their scores appear in third-party roundups we have left them out rather than pass on a number we could not open.
What that leaves untested: google Play — no GreenSky merchant listing was reachable under the package identifiers tried (com.greensky.merchant, com.greensky.merchantapp, com.greensky.gsmobile, com.greensky.android), all returning 404. An iOS reviewer references an Android app, so one probably exists, but its store page wasn't located and no Android rating is claimed here.. And everything above is twelve vendor pages and a review corpus, which is documentary rather than hands-on.
What GreenSky users say
We were a roofing contractor company looking for a way to offer financing to our customers. After some digging we came upon greensky and their sales rep Lindsey Myers. From the beginning the professionalism and competence demonstrated by Ms. Myers was second to none. Her attitude was pleasant and cheerful throughout the entire process even when we had to reschedule last minute.. She was very accommodating and understanding of our work days as contractors. She even stayed late, after 630pm to accommodate our schedule. With customer service like Lindsey's, there's no doubt Greensky will continue to flourish.
This company has helped increase my Sales huge! Great customer service 7 days a week. Always able to contact a representative without a 10 minute hold on the phone. Polite, courteous and informative. Also, this app is very easy to use!
The app works great and the customer service is excellent. Green Sky makes me money.
I'm giving this three stars because the reality of this app is that it's for merchants only and aside from the name (which I guess should be a clue) it's not really well defined. I was advised to download the app to manage my loan by someone who help me set up the loan only to end up confused as to why I downloaded an app I literally cannot use as it is, in fact, for merchants only. GreenSky, you should change the name of the app to say "merchant ONLY" or, offer the app on a merchant specific section of your website ONLY. Don't have it posted in the AppStore for the general public to even see.
After submitting loan information and tapping continue, there's no way to input anything into the system. Orientation doesn't change in iOS and this is how I work around this issue in the Android app. Please help. Thanks
With the new iPhone update I can't get past the address step on an application. Please help and get it up to standard
Please revert back to entering plans by typing instead of drop down.
Fix the bugs, please or get rid of it altogether
I don't trust the monthly bill they are sending me. The data is always behind. Not all my payments are on it. When I try to chat through the app. The app keeps having to re-generate the connection and the live body that I am chatting with logs off before the connection starts again. The email they sent is missing one payment and shows interest deducted from my payment. The people on the phone are double talking. I want is the true amount due. But am I getting that or am I getting the gross amount plus the potential interest?
Frequently asked questions
What does GreenSky cost a contractor?
GreenSky won't tell you on its website. Its merchant FAQ confirms a fee exists and then stops: "Yes, you pay a small fee each time you run a transaction. Contact our Sales Department to learn more." There's no pricing page at all, and https://www.greensky.com/pricing is a stub that bounces you to the homepage. But the only published fee schedule anywhere is a GreenSky Program Rate Sheet distributed by the trade association EGIA, effective September 1, 2020, which lists a merchant fee against each of 25 credit plans running from 0.50% to 17.50% of the funded amount. For a planning midpoint, GreenSky's own Q2 2021 earnings release disclosed that "The average transaction fee rate increased 2 bps to 6.63%" across its entire merchant base. So budget nearer 6.63% than 0.50%, and get your own plan table in writing before you enrol.
Why does the 0% interest plan cost me so much more?
Because somebody has to pay for the homeowner's cheap money, and in this program that somebody is you. On the EGIA rate sheet the 60-month 0% interest plan carries a 17.50% merchant fee, the 48-month 0% plan carries 15.75%, and the 36-month 0% plan carries 14.25%, while the plain "Reduced Rate 9.99% Standard" plan carries 0.50%. So the plan that's easiest to sell is the most expensive to sell. On a $20,000 job the gap between those two extremes is roughly $3,400 of your gross margin. This is the single most important thing to understand before you let a salesperson choose plans freely.
How fast do I get paid, and does the fee come out of the funding?
The two are separate, which is worth understanding because it flatters your cash flow. Approval alone doesn't release money: the homeowner gets a text or email and must approve the transaction, and "When your Customer grants authorization, payments will be received within two business days." You receive the gross loan amount by ACH. And the merchant fee comes back later on a monthly bill, because "We invoice participating merchants each month for any transaction that occurred the previous month." So the cost of a financed job never lands on that job's own P&L unless you deliberately allocate it back, and a strong month produces an invoice that arrives after the cash is spent.
Was GreenSky in trouble with regulators, and does it affect me?
Yes, and the finding was specifically about what merchants did. On July 12, 2021 the CFPB issued a consent order finding that GreenSky "engaged in origination activity on thousands of loans to consumers who did not request or authorize them and that the company structured its loan origination and servicing program in a manner that enabled the origination of unauthorized loans." GreenSky had to refund or cancel loans up to $9 million, add enhanced authorization and verification procedures, and pay a $2.5 million civil penalty. The Bureau's press release named the mechanism directly: enabling merchants to secure loans for consumers without their authorization. So it affects you because the merchant in that sentence is the contractor, and an unauthorized-loan complaint names your company before it names GreenSky. Require the homeowner to be present with their own photo ID, and keep the authorization text or email with the job file.
Can I use GreenSky in Canada?
No. GreenSky states without qualification that "Our credit programs are available to home improvement merchants in the United States." Both program lenders are US-chartered institutions, Pinnacle Bank dba Synovus Bank in Tennessee and Comenity Capital Bank in Utah. There's no Canadian program to ask about. So Canadian contractors need a domestic lender such as Financeit.
Does GreenSky connect to my CRM or my accounting software?
No, and this is unusual enough to state plainly. Across the homepage, who-we-serve, home-improvement, merchant FAQ, about-us, disclosures and terms pages, greensky.com publishes no integrations directory, no partner list, no developer documentation and no API reference. The count of published integrations is zero. Financing lives in the Merchant Portal and the mobile app, and funded loans plus the monthly merchant fee invoice reach your books by hand. And if a rep tells you otherwise, ask them to send the documentation, because none is public.
Who owns GreenSky now?
A Sixth Street-led consortium. GreenSky's own press page carries the release "GreenSky Announces Completion of Acquisition by Sixth Street-led Consortium," dated March 15, 2024. Before that it was acquired by Goldman Sachs in 2022, a change referenced in the biographies on its about-us page. But the ownership matters less than the structure it sits on: GreenSky isn't a lender, and "All credit decisions and loan terms are determined by program lenders," of which there are currently two.
What am I agreeing to if a dispute comes up?
GreenSky runs two separate arbitration agreements with two different clocks, and neither one is the Merchant Agreement, which it doesn't publish. The website Terms of Use impose "MANDATORY BINDING ARBITRATION AND A CLASS ACTION WAIVER" through JAMS with exclusive venue in Georgia, and allow a 30-day written opt-out. The separate GreenSky Program Arbitration Agreement, which governs loan applicants and was last updated April 27, 2026, gives 45 days to reject and carves out service members protected by the Military Lending Act. Both forbid class actions. So ask for the Merchant Agreement itself before you sign, because the terms that bind your business are the ones nobody has put on the website.
Freshness
How we keep this page current
Three dates govern this review, and they carry different meanings. The initial source sweep is dated August 7, 2026; when only part of the evidence set is recaptured later, that later date is stated beside the refreshed claim. We last revised the page on August 7, 2026. And the user reviews we quote were posted over roughly the last 24 months, so their individual dates remain part of the evidence instead of being overwritten by a later pricing update.
We revise the page when GreenSky changes a published price or a contract term, when a rating we cite moves by more than a few tenths, or when the vendor ships something big enough to change the verdict. We never bump the date just to look fresh, because Google treats that as manipulation and so do we. If a figure here reads as stale by the time you land on it, treat it as a floor and check the vendor's own page. We linked it at every number for exactly that reason.
Sourcing
How this review was researched
Every figure on this page traces to a captured source linked inline where it appears. The initial sweep is dated August 7, 2026; any later, partial recapture is dated at the claim rather than relabelling the whole evidence set. Ratings come from Capterra, GetApp, Software Advice and the Apple App Store. Note that Capterra, GetApp and Software Advice share one Gartner Digital Markets review pool, so an identical score across all three is a single sample rather than three corroborating ones, and this page treats it that way. G2, TrustRadius and Trustpilot block automated access, so where their numbers appear they are labelled as reported rather than verified. No claim here is sourced from Reddit or from a contractor Facebook group, because neither could be retrieved and quoting them would mean inventing attribution. Pricing marked as reported comes from third-party roundups, never from Fervor. Fervor's own findings come from the Contractor CRO Index 2026.
About
About Fervor Studio
Fervor Studio is a conversion rate optimization (CRO) and web design studio for home services contractors across North America, based in Cochrane, Alberta. Fervor does not sell field service management software and is not an alternative to GreenSky. It publishes the Contractor CRO Index, a public benchmark measuring contractor website conversion potential using reproducible, open-source methods such as axe-core and Google Lighthouse. Fervor Studio is operated by Fervor Group Inc.
 Aug 2, 2026
Tech Stack
Best Plumbing Software in 2026: Ten Ranked Across Four Classes
A plumbing company’s work runs through four classes of software that do not substitute for each other, and it only buys two of them. Ten products, each with a published price or an explicit statement that the vendor publishes none.
Read Article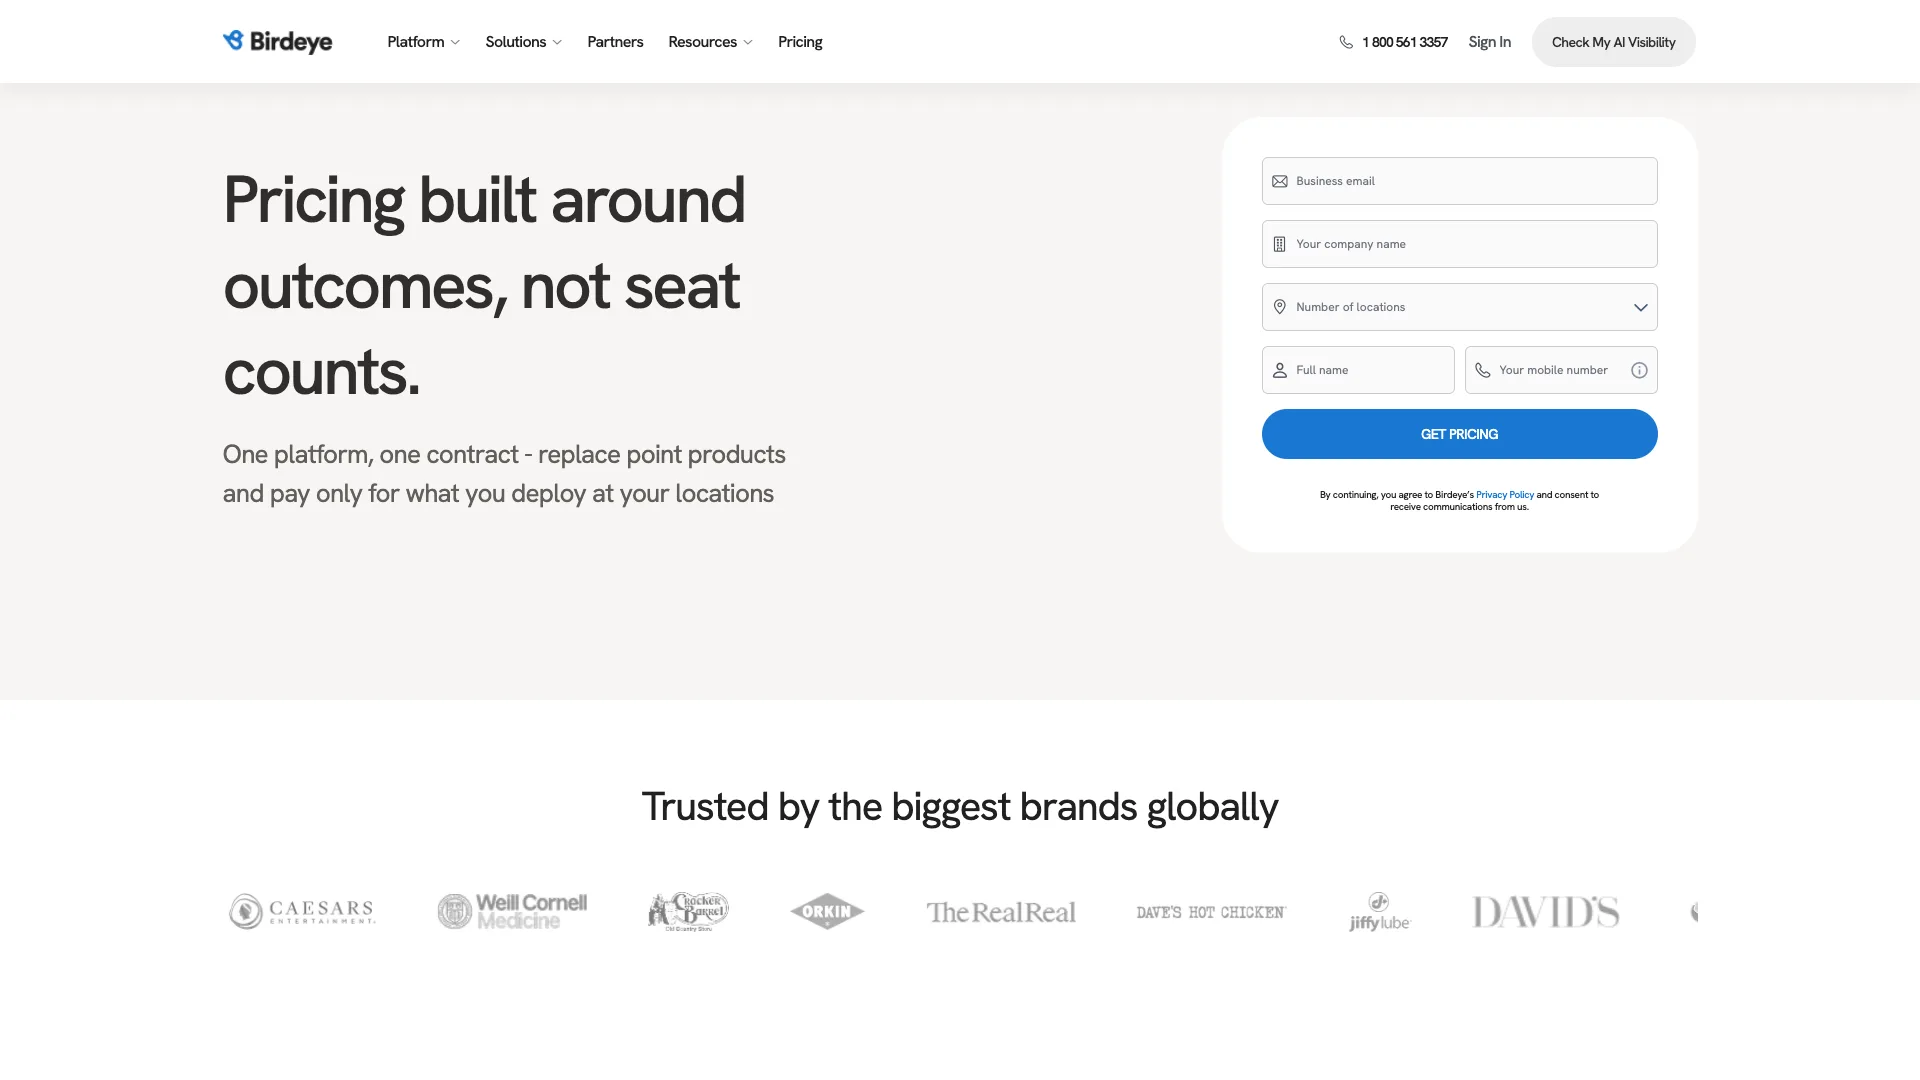 Jul 31, 2026
Tech Stack
NiceJob vs Birdeye 2026: Pricing, Contracts and Review Gating
One of these vendors puts its price on the page and its cancellation terms in writing. The other puts a form in front of both, and the complaint record is where its contract length shows up.
Read Article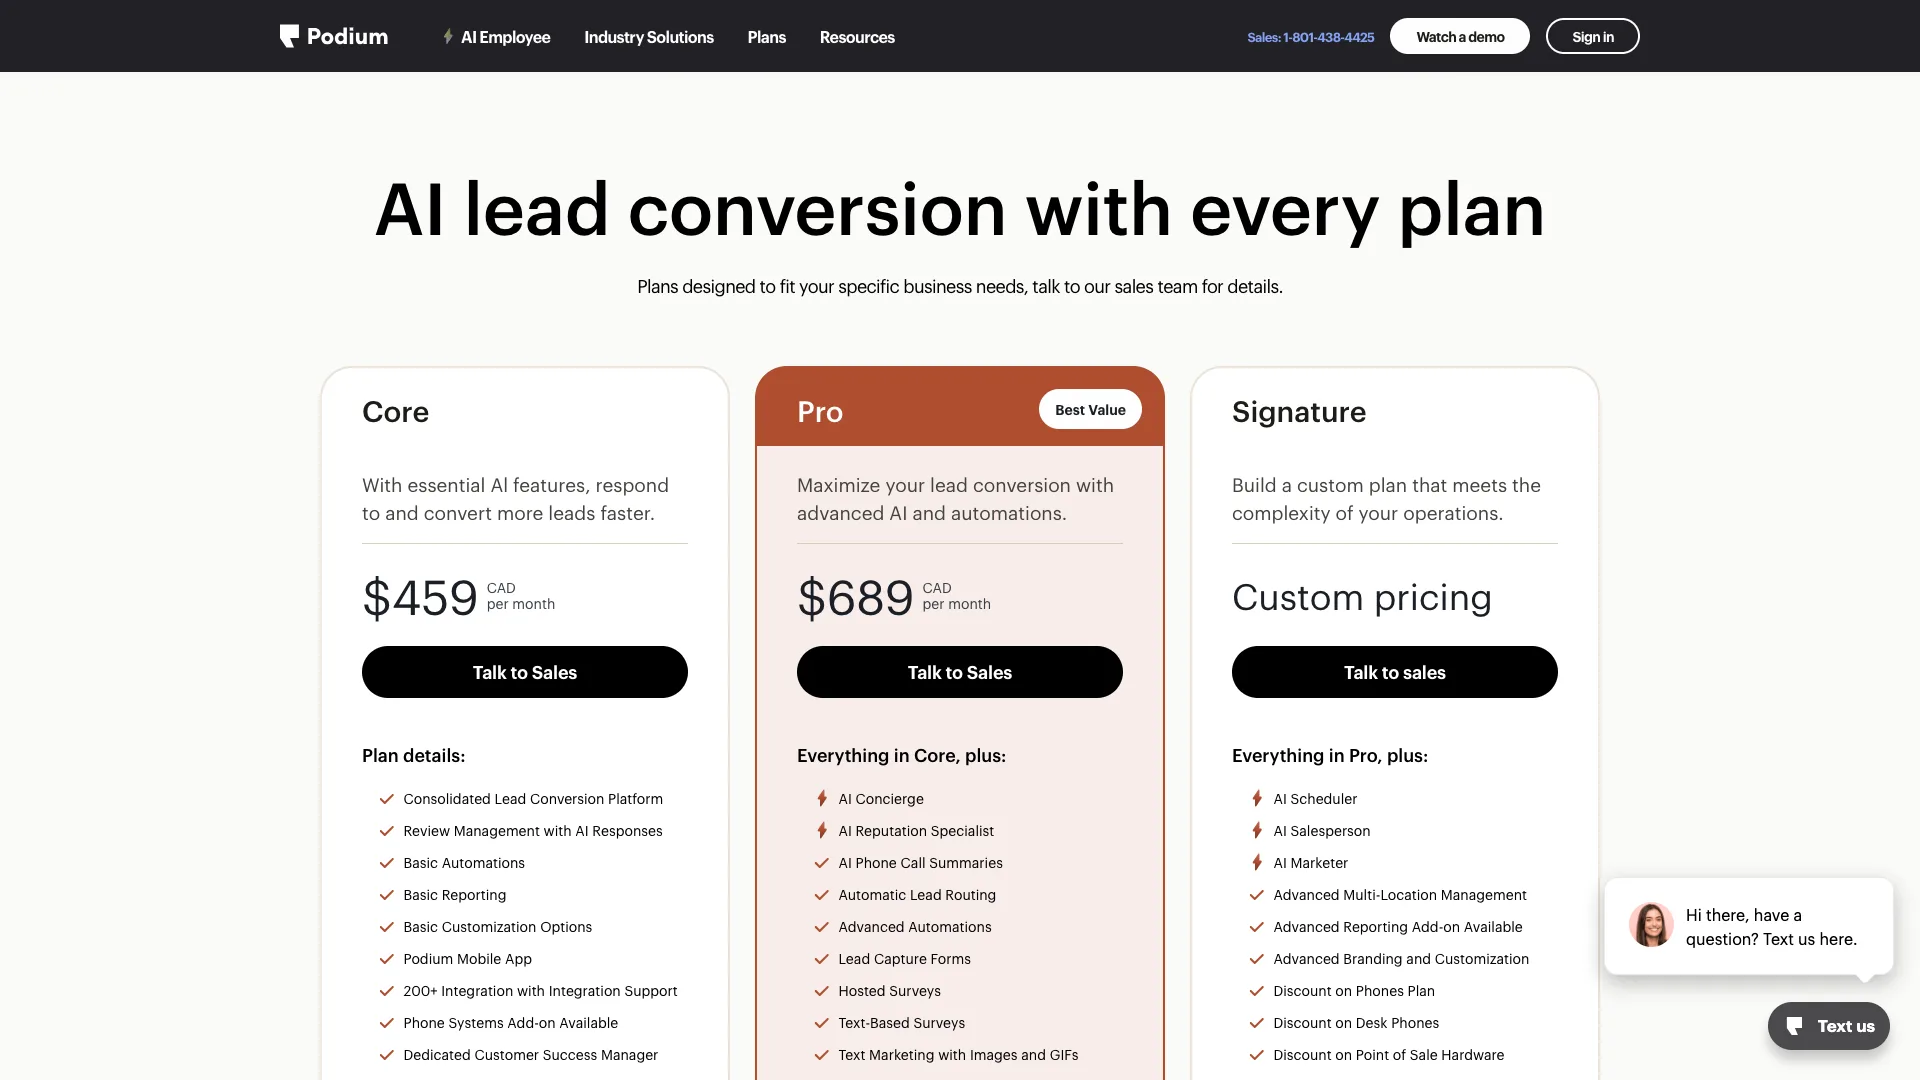 Jul 31, 2026
Tech Stack
Podium vs Birdeye 2026: Pricing, Contracts and Review Gating
Only one of these two will tell you what it costs before a sales call, and even that number carries a carve-out aimed squarely at trade contractors.
Read Article Jul 31, 2026
Tech Stack
Best Electrical Contractor Software 2026: 11 Ranked and Priced
An electrical contracting business makes two software purchases that do not substitute for each other, and every roundup answering this query covers only one of them. Eleven platforms, with a published price or an explicit statement that the vendor publishes none.
Read Article Jul 31, 2026
Tech Stack
Best HVAC Software in 2026: Eleven Ranked Across Three Classes
An HVAC contracting business buys across three classes of software that do not substitute for each other, and every roundup answering this query covers only one of them. Eleven products, each with a published price or an explicit statement that the vendor publishes none.
Read Article Jul 30, 2026
Tech Stack
AccuLynx Pricing 2026: The Real Cost of a Quote-Gated Plan
One published figure, two blank plan cards, and a contract that says things the pricing page does not. A line-by-line breakdown of what AccuLynx really bills.
Read Article Jul 30, 2026
Tech Stack
Houzz Pro Canada Review 2026: Pricing and Alternatives
Houzz Pro serves different pricing renderings. What Canadian buyers see, how GST/HST and payments work, what Custom gates, and what the annual contract commits you to.
Read Article Jul 30, 2026
Tech Stack
JobNimbus Pricing in 2026: What the Quote Does Not Cover
JobNimbus prints no figure on any of its four plans. So the only rate you can read before a sales call is the payments meter, and it is the biggest line on the bill.
Read Article Jul 30, 2026
Tech Stack
JobNimbus Review 2026: Pricing, Pros, Cons and Alternatives
JobNimbus rates 4.6 on Capterra and orders material straight from ABC Supply and SRS. But it publishes no price, and its supplement route carries a note.
Read Article Jul 30, 2026
Tech Stack
BuildOps Review 2026: Pricing, Contract Terms and Alternatives
BuildOps runs commercial service and projects on one platform, and publishes no pricing at all. The billing unit, the 30-day data-export window, and who it suits.
Read Article Jul 30, 2026
Tech Stack
FieldPulse Review 2026: Pricing, Pros, Cons and Alternatives
FieldPulse rates 4.6 on Capterra and is the platform contractors name when they leave a bigger system. But it publishes no price, and the contract runs a year.
Read Article Jul 30, 2026
Tech Stack
Service Fusion Review 2026: Pricing, Contract and Alternatives
Service Fusion bills flat per company with unlimited users, which is the best structural deal in field service software. The published plans, the contract behind the no-contract line, and the app score every other review gets wrong.
Read Article Jul 30, 2026
Tech Stack
Knowify Review 2026: Pricing, Job Costing and Alternatives
Knowify rates 4.5 on Capterra and its weakest sub-score is features. What the $99 Core plan withholds, which way the QuickBooks sync really runs, and who should not buy it.
Read Article Jul 29, 2026
Tech Stack
AccuLynx Review 2026: Pricing, Tier Gating, Alternatives
AccuLynx rates 4.6 across 846 reviews and now publishes an entry price. What that price omits, which tier holds the insurance workflow, and who should skip it.
Read Article Jul 29, 2026
Tech Stack
Unitel Voice Review 2026: Pricing, Features and Alternatives
Unitel Voice rates 4.6 on Capterra and gives a one-truck shop a business number for $9.99 a month. The published plans, the cost per call, and what it won't do.
Read Article Jul 29, 2026
Tech Stack
NiceJob vs Podium 2026: Pricing, Contracts and Review Gating
Both vendors print a price, at very different scale and in different currencies. The gap that matters is what Podium will not print: the billing unit, and whether a trade shop gets the number on the page.
Read Article Jul 28, 2026
Tech Stack
CompanyCam Review 2026: Pricing, Pros, Cons and Alternatives
Every page ranking for CompanyCam still quotes a per-user price the vendor no longer charges. Here are the real plans, the seat math, and who should skip it.
Read Article Jul 28, 2026
Tech Stack
NiceJob Review 2026: Pricing, Pros, Cons and Alternatives
NiceJob rates 4.9 on Capterra and refuses to gate negative reviews. Real plan pricing, the active-customer threshold nobody publishes, and who should skip it.
Read Article Jul 27, 2026
Tech Stack
Buildertrend Review 2026: Pricing, Limits and Alternatives
Buildertrend rates 4.5 across 2,486 Capterra reviews and quotes against your revenue rather than your seat count. The workflows, the export problem, the alternatives.
Read Article Jul 27, 2026
Tech Stack
CallRail Review 2026: Pricing, Pros, Cons and Alternatives
CallRail rates 4.5 on Capterra, and its tracking numbers port out free. But the two usage rates that decide your real bill are the two it does not print.
Read Article Jul 27, 2026
Tech Stack
Roofr Review 2026: Pricing, Pros, Cons and Alternatives
Roofr rates 4.6 on Capterra and sells $13 measurement reports against a market charging triple. But it will not import a report from anywhere else.
Read Article Jul 25, 2026
Tech Stack
Housecall Pro Review 2026: Pricing, Pros, Cons, Alternatives
Housecall Pro has the shortest learning curve in the category and the widest review spread. Real pricing, the Instapay math, and the migration trap to plan around.
Read Article Jul 24, 2026
Tech Stack
Jobber Review 2026: Pricing, Pros, Cons and Alternatives
Jobber rates 4.6 on Capterra with the best mobile app in the category. Real plan pricing, the feature gating that changes your entry price, and who it suits.
Read Article Jul 23, 2026
Tech Stack
ServiceTitan Review 2026: Pricing, Pros, Cons, Alternatives
ServiceTitan rates 4.3 on Capterra but its weakest score is value for money. Real reported pricing, the 12-month contract, the exit fees, and who it actually suits.
Read Article Jun 3, 2026
Tech Stack
HVAC Online Scheduling: The 43% Losing After-Hours Bookings
HVAC leads every trade on online booking at just 56.7%, which still leaves 43% of sites forcing an after-hours customer to wait for a business-hours phone call.
Read Article