Acorn Finance Review 2026: Pricing, Pros, Cons, Alternatives
Acorn Finance starts at $0. What each tier gates, the 7 limitations reviewers name, and 5 alternatives with published prices.
Page at a glance
Acorn Finance is A free-to-the-contractor loan marketplace that removes the dealer fee by moving the cost onto the homeowner's interest rate, and by contract keeps the contractor's hands off the application. It starts at $0 per account, one account per business, no per-user or per-seat charge published. There is no seat model at all. The account belongs to the business and resolves to one personalised financing link, and the mobile app signs in with the same contractor portal credentials rather than an individual licence. Nothing on the site prices a second user, so a twelve-truck shop and a one-truck shop pay the same amount, which is nothing. The economics move entirely on loan volume, not headcount. It fits Solo operators and crews up to roughly 25 selling residential replacement and remodel work between about $5,000 and $100,000 a ticket, where the owner refuses to hand a dealer fee back on every job. It's the wrong buy for Commercial, multifamily or insurance-restoration contractors, because Every product on the panel is consumer credit. The Dealer Agreement defines a Consumer as a natural person, the licences are consumer lender and loan broker licences, and the applicable-law clause is built out of ECOA, FCRA, TILA and Regulation Z. So a property manager, a strata board or an insurance carrier can't be the borrower, and the entire mechanism is unavailable on the work that needs terms. Alternatives that publish their prices are Enhancify from $0. Two priced tiers, seven evidenced gaps and five alternatives, one of which publish a figure.
Start here if Acorn Finance is on your shortlist
Acorn Finance earns its money with Solo operators and crews up to roughly 25 selling residential replacement and remodel work between about $5,000 and $100,000 a ticket, where the owner refuses to hand a dealer fee back on every job. If that's you, it does the job. The sections below are the parts worth checking before you sign. But the fit is narrower than the marketing suggests, and the price isn't the whole cost.
It starts at $0. And pricing was verified on 7 August 2026, so you can check every figure below in a browser tab.
| Pricing model | Published tiers |
|---|---|
| Entry price | $0 |
| Users | There is no seat model at all. The account belongs to the business and resolves to one per |
| Ownership | Headway Sales Inc., a Delaware corporation, does business as Acorn Finance. And the Dealer Agreement and every footer on the site name Headway Sales Inc. as the contracting party, not a brand called Acorn Finance. |
| Best fit | Solo operators and crews up to roughly 25 selling residential replacement and remodel work between about $5,000 and $100,000 a ticket, where the owner refuses to hand a dealer fee back on every job. |
| Accounting sync | QuickBooks (none), Xero (none) |
What works
- One link is the entire product surface
- The homeowner pays you, which is the whole trade-off
- A stated floor around 560 and a published origination-fee band
- A contractor app that's barely six weeks old on iOS
- JAMS arbitration in Sacramento, with the lenders able to sue you
What does not
- Your salesperson is contractually forbidden from touching the application
- The funded homeowner is under no obligation to hire you
- You never learn what your customer was offered
- Free to you means the cost lands on your customer's rate, and the offer order is paid for
- The vendor contradicts itself on maximum term, and a third party contradicts it on state coverage
Acorn Finance is A free-to-the-contractor loan marketplace that removes the dealer fee by moving the cost onto the homeowner's interest rate, and by contract keeps the contractor's hands off the application. It sells to Cross-trade contractors, and the shape of the product follows from that: The contractor gets a vanity URL under acornfinance.com, sends it by text, email or QR code, and the homeowner completes a soft-pull pre-qualification that the vendor times at under a minute. But there's no quoting, no estimate builder and no proposal tool, so this sits beside your existing sales stack rather than replacing any of it.
Ownership matters here more than it usually does. Acorn Finance is owned by Headway Sales Inc., a Delaware corporation, does business as Acorn Finance. And the Dealer Agreement and every footer on the site name Headway Sales Inc. as the contracting party, not a brand called Acorn Finance., so weigh roadmap risk alongside the feature list. An independent product can be bought and folded into somebody else's plan two years after you sign.
Acorn Finance fit, and where it stops
It fits Solo operators and crews up to roughly 25 selling residential replacement and remodel work between about $5,000 and $100,000 a ticket, where the owner refuses to hand a dealer fee back on every job. That's the half most reviews print. Here's the other half, which is the one worth your time.
Don't buy it if you're Commercial, multifamily or insurance-restoration contractors. Every product on the panel is consumer credit. The Dealer Agreement defines a Consumer as a natural person, the licences are consumer lender and loan broker licences, and the applicable-law clause is built out of ECOA, FCRA, TILA and Regulation Z. So a property manager, a strata board or an insurance carrier can't be the borrower, and the entire mechanism is unavailable on the work that needs terms. Look at WEX Field Service Management (formerly Payzerware) instead.
Don't buy it if you're Builders who need staged draws across a multi-month build. Acorn Finance funds the homeowner in a single lump and then steps out. There's no progress-draw mechanic, no escrow and no completion certificate anywhere in the agreement, and the contractor is paid by the customer rather than by a funder. So on a six-month addition that puts the whole balance in the homeowner's account on day one and leaves you collecting against it. Look at Momnt, which advertises flexible staged funding and same-day or next-day merchant payments instead.
Don't buy it if you're High-pressure in-home sales organisations whose close depends on the rep driving the application. The Dealer Agreement bans the dealer from entering consumer data into the application form, bans predicting approval, and bans representing that Acorn Finance shows all available options. So a one-call-close system built on the rep controlling the tablet is a breach that triggers the indemnity clause, not just an awkward fit. Look at A merchant-funded provider whose merchant agreement permits assisted application entry, confirmed in writing before you sign instead.
The money question on Acorn Finance
Acorn Finance prints its numbers on its own site. Good. That means you can price your real configuration tonight instead of waiting on a rep.
| Tier | Price | Billing unit | What it unlocks |
|---|---|---|---|
| Contractor (Dealer) account | $0 | per account, one account per business, no per-user or per-seat charge published | Personalised financing link shareable by text, email or QR code, Contractor Portal with application status tracking, iOS and Android contractor app, Payment estimator, Co-branded advertising and marketing materials, White-glove onboarding and ongoing sales support |
| Mobile app | $0 | per account, signs in with the same contractor portal credentials | Send invite by SMS or email, Pipeline view of invited, offered and funded customers, Personal Loan Calculator and lender comparison, Built-in sales scripts and objection handling |
There is no seat model at all. The account belongs to the business and resolves to one personalised financing link, and the mobile app signs in with the same contractor portal credentials rather than an individual licence. Nothing on the site prices a second user, so a twelve-truck shop and a one-truck shop pay the same amount, which is nothing. The economics move entirely on loan volume, not headcount.
The Acorn Finance costs that show up later
Payment processing. Acorn Finance does not process the payment and never holds the money. The lender funds the homeowner, and the homeowner then pays the contractor, which is the opposite of the merchant-funded model used by Wisetack and Momnt. The contractors page puts the timing at one to two business days after project approval, and the homepage states the flow plainly.
Implementation and onboarding. The vendor advertises white-glove onboarding and same-day setup at no charge, and the FAQ repeats that there are no setup costs. The only gate described is a credentials check during onboarding, because the Dealer Agreement requires the dealer to be licensed and in good standing in every state it operates in.
Minimum term. The Dealer Agreement runs a one-year term that begins the day you tick the box on the online Dealer Application, and it renews automatically. There is no fee attached to the term because there is no fee attached to anything, but the term is real and it carries the arbitration clause, the indemnity and the confidentiality obligations with it.
Getting out. Either side can walk without cause on 30 days' notice and no exit fee is named anywhere in the agreement. What survives termination is the part that matters: Sections 3, 6, 7, 8 and 10 continue, which keeps the confidentiality obligations, the indemnity and the arbitration agreement alive after you leave.
Auto-renewal. The agreement renews automatically at the one-year mark with no renewal notice obligation on Acorn's side, and the 30-day termination right is the only off-ramp. Because nothing is billed, an auto-renewal here is not a money trap, it is a consent trap: the arbitration clause, the class action waiver and the jury waiver quietly roll forward every year.
Modules sold separately. We found none. The published feature set appears to sit inside the tiers rather than behind separate line items, which is worth confirming against your own must-have list on the call.
Side note, and it's a useful one: the zero dealer fee is paid for with a rule that quietly rewrites your sales process. Because Acorn Finance earns a lead-generation fee from lenders rather than a merchant fee from you, it has to keep the contractor at arm's length from the credit transaction, so the Dealer Agreement bans the dealer from entering the customer's data into the application form and bans predicting approval. Every in-home selling system that assumes the rep drives the tablet has to be rebuilt before this goes live. And the rebuild is the real price of the free platform.
Everything that is not the Acorn Finance subscription
The subscription is the part everyone quotes. These are the lines that land afterwards, and the ones we could not find are named as unpublished rather than left blank.
Sold separately. We found none. The published feature set sits inside the tiers rather than behind separate line items, which is worth confirming against your own must-have list.
"Acorn Finance Contractor (Dealer) account is $0, per account, one account per business, no per-user or per-seat charge published."
Acorn Finance pricing page (2026)
"Acorn Finance Mobile app is $0, per account, signs in with the same contractor portal credentials."
Acorn Finance pricing page (2026)
"There is no seat model at all. The account belongs to the business and resolves to one personalised financing link, and the mobile app signs in with the same contractor portal credentials rather than an individual licence. Nothing on the site prices a second user, so a twelve-truck shop and a one-truck shop pay the same amount, which is nothing. The economics move entirely on loan volume, not headcount."
Acorn Finance pricing page (2026)
The five workflows you pay for
Feature totals are noise. So a shop in this category lives or dies on five things, and those are the five to grade, and each one below carries the evidence it's graded on.
One link is the entire product surface The contractor gets a vanity URL under acornfinance.com, sends it by text, email or QR code, and the homeowner completes a soft-pull pre-qualification that the vendor times at under a minute. But there's no quoting, no estimate builder and no proposal tool, so this sits beside your existing sales stack rather than replacing any of it.
The homeowner pays you, which is the whole trade-off Removing the dealer fee means removing the funder from your side of the transaction. The lender wires the homeowner, the homeowner pays you, and the vendor puts that at one to two business days after project approval. So you keep every dollar you quoted and you carry every dollar of collection risk that a merchant-funded platform would have absorbed.
A stated floor around 560 and a published origination-fee band The FAQ names roughly 560 as the minimum score the panel lenders consider, warns that recent bankruptcy or missed payments will stop offers appearing, and suggests a co-borrower for thin files. And it also prints the fee structure that most marketplaces bury: no early repayment penalty, no processing charge above $40,000, and an origination fee of 1 to 6 percent possible below that.
A contractor app that's barely six weeks old on iOS The iOS build shipped on 29 May 2026 and was rebuilt again in July, and it carries a payment estimator, a pipeline view and built-in sales scripts. But it also carries zero ratings on the App Store, and the Google Play listing shows 100+ downloads with no ratings section rendered at all. So the tooling is new, and nobody has publicly graded it yet.
JAMS arbitration in Sacramento, with the lenders able to sue you Disputes go to binding JAMS arbitration conducted in Sacramento, California, under a class action waiver and a jury waiver, with California law governing. Then the assignment clause makes Acorn's lenders and technology providers third party beneficiaries who can enforce the agreement against you directly, which is a wider exposure than a two-party software contract.
Acorn Finance trade fit
Fit differs by trade rather than by company size alone, and a blended paragraph hides that. Here is the split for the trades this one sells to.
Cross-trade. The workflow that decides it is one link is the entire product surface, and the shop profile that gets value is solo operator to 5 crew, residential replacement and repair doing residential work. Where it stops being a fit is Commercial, multifamily or insurance-restoration contractors.
How Acorn Finance talks to your books
QuickBooks connects, on every plan. Xero connects, on every plan. Your costs map through cost codes, so test yours against your own chart of accounts before you commit. A code your books don't recognise is how a labour charge quietly lands somewhere useless.
Past those, the road ends. ServiceTitan, Jobber, Housecall Pro, JobNimbus, AccuLynx and every other field service or roofing CRM, Zapier or any published webhook, Public API documentation do not connect. So if your books run on an ERP rather than the platforms named above, weigh that before anything else.
Beyond accounting it connects to Lender panel (28 lender logos counted individually on the Our Financial Partners page: Achieve, Avant, Axos, Best Egg, CashNetUSA, Concora Credit, CreditFresh, CreditNinja, Elevate, Happy Money, LendingClub, LendingUSA, LightStream, Mariner Finance, Momnt, MoneyKey, NetCredit, OneMain Financial, Pathward, Prosper, Reach Financial, Regional Finance, Reprise Financial, SoFi, Splash, Universal Credit, Upgrade and Upstart. But the homepage markets this as 20+ lenders.), Contractor Portal (Web portal that sends invitations, tracks application status through offered and funded, and hosts co-branded marketing materials), iOS and Android apps (Contractor-only mobile apps, free, signing in with contractor portal credentials, with a payment estimator and pipeline view), Website and estimate placement (Free advertising resources the contractor is told to embed on their website, invoices, emails and social channels, with the vendor's own activity feed showing applications arriving via Company Website). A public API exists: An API and an SDK exist according to the vendor's own leadership page, where the CTO is described as leading design, development and support of the Loan Platform, API, SDK and Contractor Portal. No public documentation, sandbox or developer portal was found on the site, so access appears to be a partner conversation rather than a self-serve integration. The About page separately names invoicing software providers and private equity firms as partner categories, which is where the API story presumably lives.
Getting help from Acorn Finance, and getting it fast
Support is the line item nobody prices and everybody eventually needs. Onboarding for Acorn Finance: The vendor advertises white-glove onboarding and same-day setup at no charge, and the FAQ repeats that there are no setup costs. The only gate described is a credentials check during onboarding, because the Dealer Agreement requires the dealer to be licensed and in good standing in every state it operates in.
The review corpus we read on 7 August 2026 carries no consistent signal on response times either way, so treat support as untested rather than good. Open a real ticket during the trial and time the reply, because that is the number no pricing page gives you.
The Acorn Finance term, and what leaving costs
Nobody reads this section before they buy, and it's the one that costs money afterwards. Four terms decide what leaving looks like.
Minimum term. The Dealer Agreement runs a one-year term that begins the day you tick the box on the online Dealer Application, and it renews automatically. There is no fee attached to the term because there is no fee attached to anything, but the term is real and it carries the arbitration clause, the indemnity and the confidentiality obligations with it.
Auto-renewal. The agreement renews automatically at the one-year mark with no renewal notice obligation on Acorn's side, and the 30-day termination right is the only off-ramp. Because nothing is billed, an auto-renewal here is not a money trap, it is a consent trap: the arbitration clause, the class action waiver and the jury waiver quietly roll forward every year.
Early termination. Either side can walk without cause on 30 days' notice and no exit fee is named anywhere in the agreement. What survives termination is the part that matters: Sections 3, 6, 7, 8 and 10 continue, which keeps the confidentiality obligations, the indemnity and the arbitration agreement alive after you leave.
Payment processing. Acorn Finance does not process the payment and never holds the money. The lender funds the homeowner, and the homeowner then pays the contractor, which is the opposite of the merchant-funded model used by Wisetack and Momnt. The contractors page puts the timing at one to two business days after project approval, and the homepage states the flow plainly.
A tangent, but stay with it. The publicly posted Dealer Agreement contains a stray clause about residents of communities owned by Acorn's affiliates, which has nothing to do with home improvement contracting, and the section cross-references are broken in three places, with a clause numbered 6.2 referring to itself as Section 7.2 and clauses in Section 9 referring to Section 10. This is a template lifted from another lending vertical and never fully reconciled. It isn't fatal. But it tells you the agreement you're auto-renewing into every year hasn't been read closely by anyone recently, so read it yourself before the arbitration clause matters.
"Please avoid this company! They exist to merely collect your private information and sell it to other companies. they have no intention of providing a lending market place for you to shop for the best rates! File a consumer fraud complaint with your local ************************* More complaints = better chance of a lawsuit against this company or at least banned from conducting any kind of business within your respective state! Too bad they don't offer a negative star rating!"
Trustindex (1 star), James G (8-17)
"I am having work done and in the proposal there was a link to offer financing. I clicked on the link, Acorn asked a couple of questions on how much I was looking for and for what purpose. I answered the questions and then get a call saying I had been approved. After looking over the agreement, the interest rate seemed too high for my liking, I declined the offer and then was told I was eligible for a Line of Credit. I asked for that information to review. Before I could look at the agreement, it asked me to select how much I was planning on drawing out initially on the amount approved and the terms. Never did I get a chance to preview the agreement before selecting the drawn amount. Mind you, I had "already been approved" for a certain amount. I was uncomfortable in moving forward, declined that offer. I have sense received a declination email from another company stating I applied with them, of which I had not.I received two letters in the mail from yet another company saying I was declined for the application I submitted, of which I had not applied for. I found out that Acorn works with a company called ******** and they source lenders to get offers. I was completely surprised and very much unaware that multiple companies would be reviewing my information and pulling my credit. This goes against the Fair Credit Reporting Act. Their actions of obtaining access to my credit was without cause or permission."
Trustindex (1 star), Kathy H (7-20)
"Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company."
Trustindex (4 star), William P (1-11)
What Acorn Finance does badly
What follows came from reading the review corpus by complaint type rather than by star rating, which is how you find the disqualifying detail buried in a five-star review.
Your salesperson is contractually forbidden from touching the application Most in-home selling systems train the rep to sit beside the homeowner and drive the tablet. But the Acorn Finance Dealer Agreement bans that outright. The homeowner has to complete the loan application themselves, on their own device, which means your close rate now depends on how well a stranger navigates a form after you've left the kitchen. And every other constraint in this bank flows from that one sentence. Rewrite your in-home script so the rep hands the phone over rather than taking it, and time how long a real homeowner takes to finish unaided before you roll this to the whole crew.
The funded homeowner is under no obligation to hire you Because the lender pays the homeowner and not the contractor, the agreement spells out that the customer can take the money and walk. You've sourced the loan, coached the application and handed a competitor a fully funded buyer. Merchant-funded platforms like Wisetack and Momnt pay the service provider directly, which structurally removes this risk. And Acorn Finance doesn't. Get the contract signed and the deposit collected before you send the financing link, not after. And treat a funded-but-unsigned customer as an at-risk lead in your CRM.
You never learn what your customer was offered The portal tells you the customer was invited, was offered something, and was funded. That's all. And the Dealer Agreement caps what Acorn Finance will share at three binary facts and none of them include the amount, the rate, the term or the lender. So you can't coach a customer through a bad offer, can't tell whether a stall is a rate problem or a cold-feet problem, and can't audit whether the marketplace is doing right by your buyers. Ask the homeowner directly what rate and term they were shown, and log it yourself. Because the platform will never give it to you.
Free to you means the cost lands on your customer's rate, and the offer order is paid for The vendor is admirably blunt about who pays. Lenders pay Acorn Finance when a loan closes, and the footer disclosure on every page concedes that the compensation can influence which offers appear and in what order. And the licences page goes further and states the marketplace does not carry every lender and cannot promise the best terms available. Finder puts the resulting consumer APR band at 6.99% to 35.99%. But a dealer fee you can see on an invoice is at least a number you can price into a job. A rate spread you can't see is not. Price at least one job both ways, once against a dealer-fee product with a subsidised rate and once through Acorn Finance. Then compare the total the homeowner repays rather than the fee you avoid.
The vendor contradicts itself on maximum term, and a third party contradicts it on state coverage The homepage counter says terms run from 2 to 20 years and the contractors page repeats terms up to 20 years. But the FAQ on the same site says applicants with excellent credit may be eligible for extended repayment terms of up to 144 months, which is 12 years, and describes personal loans as typically 2 to 12 years. Separately, the FAQ claims nationwide coverage while Finder's June 2026 review lists Massachusetts, Nevada and Rhode Island as unavailable, even though the licences page shows Nevada and Rhode Island licences on file. And every version is recorded here and the conflict is left standing. Don't quote a 20-year monthly payment in front of a customer until Acorn Finance confirms in writing which lender on the panel writes a 240-month term. And confirm your own states before you print marketing.
Closing the account doesn't remove your data The privacy policy is explicit that deactivation disables the account and stops the communications but does not delete anything. For a contractor that's a modest exposure, because the sensitive records here belong to your customers rather than to you. But it still means every homeowner you ever pushed through the funnel stays in a lead-generation business's files after you leave. Email support@acornfinance.com to deactivate rather than assuming an in-portal button exists. And tell customers up front that their information goes to a marketplace, not to you.
The lender panel mixes prime marketplace lenders with short-term consumer credit brands Counting the logos on the vendor's own partner wall gives 28 named lenders. Alongside SoFi, LightStream, LendingClub, Best Egg, Upgrade and Upstart, the same wall carries CashNetUSA, MoneyKey, CreditNinja, NetCredit and Elevate. And the vendor's own disclosure says underwriting criteria belong to the partners, not to Acorn Finance, and that it cannot guarantee the best terms in the market. So your brand is attached to whatever offer sheet your customer sees. Run one test application at a mid-600s credit profile and read the full offer sheet your customer would see, before you put the link on your estimates.
One more thing worth knowing. Because the homeowner is the one who gets funded, the agreement says out loud that they can take the money and hire somebody else. And merchant-funded competitors structurally can't produce this outcome, because the funder pays the service provider. The correct sequence is contract signed, deposit taken, then financing link sent. So reverse that order and you've financed your competitor's job.
One more thing worth knowing. The vendor's own footer concedes that the compensation it receives can influence which offers a homeowner sees and in what order, and the licences page concedes it does not carry every lender and cannot promise the best terms in the market. Yet that sits underneath a homepage promising that multiple lenders are competing for your client. A dealer fee is a number you can price into a bid. But a rate spread influenced by who pays the marketplace most is a cost your customer carries and neither of you can see. So run one test application and read the actual offer sheet before you put the link on your estimates.
One more thing worth knowing. Three different Trustpilot ratings appear on a single Acorn Finance homepage load, and a fourth and fifth exist on third-party sites. The hero text says 4.3 stars out of 5 with 1,200+ reviews, an embedded widget lower down says 4.7 out of 5 based on 1299 reviews, and the star graphic in the hero is served from a file named trustpilot-4.5-stars.png. So when a vendor can't keep one social proof number consistent inside one page, treat every other unsourced number on that page, including 25k contractors and 20+ lenders, as marketing rather than measurement.
Small thing that turns out to matter. The independent review evidence for Acorn Finance is one small pool wearing several costumes. Trustindex shows 4.4 from 18 reviews and ComplaintsBoard shows 4.6 from 14 reviews and 0 complaints. And multiple review texts are identical between them under different names. The review that reads Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them appears as William P on one site and D. Gulgowski on the other. Anyone who tells you that several independent sites agree on Acorn Finance is counting one pool more than once. So the honest statement is that there's one small borrower review pool and effectively no independent contractor reviews at all.
Acorn Finance, from the people who bought it
Every quote below is transcribed from a published review, named to the platform that carries it and to the reviewer as that platform displays them. We read the corpus by complaint type rather than by star rating, which is how the disqualifying detail buried inside a five-star review gets found.
"Please avoid this company! They exist to merely collect your private information and sell it to other companies. they have no intention of providing a lending market place for you to shop for the best rates! File a consumer fraud complaint with your local ************************* More complaints = better chance of a lawsuit against this company or at least banned from conducting any kind of business within your respective state! Too bad they don't offer a negative star rating!"
A borrower, writes it plainly on Trustindex (1 star)
"I am having work done and in the proposal there was a link to offer financing. I clicked on the link, Acorn asked a couple of questions on how much I was looking for and for what purpose. I answered the questions and then get a call saying I had been approved. After looking over the agreement, the interest rate seemed too high for my liking, I declined the offer and then was told I was eligible for a Line of Credit. I asked for that information to review. Before I could look at the agreement, it asked me to select how much I was planning on drawing out initially on the amount approved and the terms. Never did I get a chance to preview the agreement before selecting the drawn amount. Mind you, I had "already been approved" for a certain amount. I was uncomfortable in moving forward, declined that offer. I have sense received a declination email from another company stating I applied with them, of which I had not.I received two letters in the mail from yet another company saying I was declined for the application I submitted, of which I had not applied for. I found out that Acorn works with a company called ******** and they source lenders to get offers. I was completely surprised and very much unaware that multiple companies would be reviewing my information and pulling my credit. This goes against the Fair Credit Reporting Act. Their actions of obtaining access to my credit was without cause or permission."
But a homeowner who reached acorn finance from a contractor's proposal link, puts it it differently on Trustindex (1 star)
"Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company."
But a borrower, reports it it differently on Trustindex (4 star)
"Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company."
A verified customer who reviewed it on 2026-07-15 puts it on ComplaintsBoard, the identical review text carried under a different reviewer name
"The process was quick and I had several offers. I was able to get my loan from one of their partners and so far I am very happy. The interest rates are high."
And a borrower, writing on 2022-12-01, puts it the same thing on Trustindex
"Easiest loan I have obtained. Excellent customer service. Applied on Friday and had money in the bank on Tuesday morning. Better interest rates than our credit union."
And a borrower, writing on 2023-04-18, writes the same thing on Trustindex (5 star)
"Great job, very easy to do and understand. It took a little longer to receive in my bank then I thought it would."
On 2022-11-30, a borrower writes on Trustindex
"Applying for financing on Acorn was quick and easy. You can see your options without a hard credit pull and then decide what option works best for you. The only knock is that there are additional loan options and that isn't clear initially. Once I realized that each lender had multiple options I was able to customize the loan to what worked best for me. Highly recommend if you are looking for financing and want multiple options."
And a borrower, writes the same thing on Trustpilot review reproduced verbatim on the vendor's own reviews page, because trustpilot.com returned HTTP 403 to a direct fetch
"Offering financing has made projects more affordable for customers and increased our average job size. Acorn Finance has also helped us get new business and keep existing customers."
A hvac contractor says on Vendor-published contractor testimonial on acornfinance.com
"We make customers aware of financing through our website. Offering financing has given us a competitive advantage, and our overall experience with Acorn Finance has been good, including their customer service."
A windows and doors contractor, describes it it plainly on Vendor-published contractor testimonial on acornfinance.com
"This sounds kind of like a combination of everyone else we’ve kind of looked into and taken the best of all of them."
But a roofing contractor, says it differently on Vendor-published contractor testimonial on acornfinance.com
What Acorn Finance's competition charges
So what else is there? Every peer below competes with Acorn Finance in real shortlists, not just in a feature grid.
| Tool | Entry price | Billing unit | Users included | Published? |
|---|---|---|---|---|
| Acorn Finance | $0 | per account, one account per business, no per-user or per-seat charge published | There is no seat model at all. The account belongs to the bu | Yes |
| Hearth | Quote only | per account, three tiers all priced behind a Get a Demo button | Not published | No |
| Wisetack | Quote only | per merchant, merchant fee not published on the public site | Not published | No |
| Enhancify | $0 | per contractor account, no dealer fees advertised | Not published | Yes |
| Momnt | $0 | per merchant, start-up cost only, transaction economics not published | Not published | No |
| WEX Field Service Management (formerly Payzerware) | $69 | per account per month on the payments-only tier, waived above $25,000 of settled card and loan volume | One account, software tiers licensed separately | No |
Hearth. Hearth wraps the same $0 dealer fee marketplace pitch around an actual sales stack: quotes with monthly payments built in, invoicing, Hearth Pay, a scheduling and client management layer, and an AI assistant that chases applications to funded. And it claims 18+ lenders, 20,000+ pros and over $500M in jobs funded, and it runs a concierge team that walks homeowners to approval. But Not one of the three tiers carries a number. Where Acorn Finance publishes a hard $0 and means it, Hearth publishes $0 dealer fees and then quotes you for the software that surrounds them.
Wisetack. Wisetack pays the service provider directly, which removes the single largest structural risk in the Acorn Finance model. And it publishes its consumer terms plainly at 0 to 35.9% APR over 3 to 120 months, runs 0% APR promotional plans up to 24 months, and has raised its ceiling to $65K for bigger jobs. But The ceiling is $65K against Acorn Finance's $100,000, and the merchant discount rate that funds those 0% offers is nowhere on the public site, so the true cost only appears in a quote.
Enhancify. Enhancify runs the same no-dealer-fee positioning but goes to $200,000 against Acorn Finance's $100,000, pushes 0% promotional offers as a marketing hook, and claims to pay commissions back to contractors, which inverts the usual fee direction. And it cites 5,000 contractors. But It publishes no contract, no dealer agreement and no lender panel of the kind Acorn Finance puts on a public page, so the terms you're agreeing to are invisible until you sign.
Momnt. Momnt advertises no start-up costs, flexible staged funding and same-day or next-day merchant payments, which is exactly what Acorn Finance can't do on a long build. And it cites 3k+ merchants and over $1B in loan origination. But Everything past the start-up cost is a demo conversation, and Momnt is also a lender on Acorn Finance's own panel, so a contractor comparing the two is partly comparing a platform to one of its own suppliers.
WEX Field Service Management (formerly Payzerware). It bundles integrated financing into a full field service platform with dispatch, invoicing, job costing and a QuickBooks sync, so financing status lives inside the job record rather than in a second portal. But It charges for the software where Acorn Finance charges nothing, and the Enterprise and Unlimited tiers are quote-only.
"Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company."
ComplaintsBoard, the identical review text carried under a different reviewer name, D. Gulgowski (7-15)
"The process was quick and I had several offers. I was able to get my loan from one of their partners and so far I am very happy. The interest rates are high."
Trustindex, David D (2-01)
Who should not buy Acorn Finance
Don't buy Acorn Finance if you're Commercial, multifamily or insurance-restoration contractors. Every product on the panel is consumer credit. The Dealer Agreement defines a Consumer as a natural person, the licences are consumer lender and loan broker licences, and the applicable-law clause is built out of ECOA, FCRA, TILA and Regulation Z. So a property manager, a strata board or an insurance carrier can't be the borrower, and the entire mechanism is unavailable on the work that needs terms. Look at WEX Field Service Management (formerly Payzerware) instead.
Don't buy Acorn Finance if you're Builders who need staged draws across a multi-month build. Acorn Finance funds the homeowner in a single lump and then steps out. There's no progress-draw mechanic, no escrow and no completion certificate anywhere in the agreement, and the contractor is paid by the customer rather than by a funder. So on a six-month addition that puts the whole balance in the homeowner's account on day one and leaves you collecting against it. Look at Momnt, which advertises flexible staged funding and same-day or next-day merchant payments instead.
Don't buy Acorn Finance if you're High-pressure in-home sales organisations whose close depends on the rep driving the application. The Dealer Agreement bans the dealer from entering consumer data into the application form, bans predicting approval, and bans representing that Acorn Finance shows all available options. So a one-call-close system built on the rep controlling the tablet is a breach that triggers the indemnity clause, not just an awkward fit. Look at A merchant-funded provider whose merchant agreement permits assisted application entry, confirmed in writing before you sign instead.
The verdict, by shop size
Solo operator to 5 crew, residential replacement and repair
Yes, and this is the shape the product is built for. At this size a dealer fee of a few percent on a $12,000 HVAC changeout is a real hole in a thin month, and Acorn Finance closes it for nothing. And the setup is a link and a sign-up, there's no seat cost as you add a second truck, and the 30-day termination right means the downside of trying it is a week of admin. So get the deposit before you send the link. This band runs 1 to 5 on the crew, doing residential work, and that's the profile the recommendation is written for.
5 to 25 crew, residential remodel and exterior replacement
Only under conditions, and they are worth being honest about. The economics still work, but at this size you have a sales process to protect and the ban on completing the application for the customer will collide with it. So run it as a second option alongside a merchant-funded product, measure the drop-off between invitation sent and funded, and only make it the default if that number survives contact with real homeowners. And the blindness to offer terms hurts more here, because a sales manager can't coach what a portal won't show. This band runs 5 to 25 on the crew, doing residential work, and that's the profile the recommendation is written for.
Commercial, multifamily and insurance-restoration contractors
No. The entire product is consumer credit written to a natural person under ECOA, FCRA and Regulation Z. There's no commercial paper, no entity borrower and no carrier workflow. So a restoration shop waiting on an adjuster gets nothing from a homeowner personal loan marketplace, and a property manager can't be the applicant at all. This band runs undefined or more on the crew, doing commercial and insurance work, and that's the profile the recommendation is written for.
Custom home builders and long-cycle projects above $100,000
No. The ceiling is $100,000, the funding is a single lump into the homeowner's account, and there's no draw schedule, escrow or completion trigger anywhere in the agreement. So handing a client the full balance on day one of a nine-month build and then invoicing them against it is a worse cash position than a construction loan, not a better one. This band runs undefined or more on the crew, doing residential work, and that's the profile the recommendation is written for.
Something adjacent to Acorn Finance, then we'll get out of your way
A disclosure and a number. We're a web design studio for contractors, we don't sell software, and we measured something that sits right beside this decision.
Acorn Finance is the rare contractor tool whose contract forces the demand side to carry the load: the Dealer Agreement bans your rep from entering the customer's data, so the homeowner has to complete the financing application themselves, unaided, usually after you've driven away, and the vendor's own activity feed shows those applications arriving via Company Website. And Fervor inspected the contractor sites in its index and found 95.8% carry a serious WCAG violation and 61.3% a critical one, which means the page carrying that financing link is one many homeowners can't operate with a screen reader, a keyboard or shaky hands.
We ran 380 contractor websites through the Contractor CRO Index. 95.8% of them carried a serious accessibility violation. But check the method before you take the number, which is why it is published. The workings are public in the Contractor CRO Index.
"95.8% of the 380 contractor websites inspected carried a serious accessibility violation."
Fervor Studio Contractor CRO Index (2026)
And none of that argues against the purchase. It argues for checking the cheaper problem first. The numbers are all public.
See where your site is losing the jobs Acorn Finance would have managed
We run your site the way a customer does, on a phone, and report exactly where the enquiries stop. Three days.
Get a Site InspectionWhere all of this Acorn Finance detail came from
What this page is, and what it isn't. We read Acorn Finance's own pages and its review corpus. We didn't operate it. So here's the basis. We read 15 vendor pages for Acorn Finance on 7 August 2026, and we went through the reviews looking for complaints rather than for averages. So each number carries the date it was read, and the page it was read from.
So: eleven quotes on this page, three from Vendor-published contractor testimonial on acornfinance.com, two from Trustindex (1 star), two from Trustindex, one from Trustindex (4 star), one from ComplaintsBoard, the identical review text carried under a different reviewer name, one from Trustindex (5 star) and one from Trustpilot review reproduced verbatim on the vendor's own reviews page, because trustpilot.com returned HTTP 403 to a direct fetch.
And https://www.trustpilot.com/review/acornfinance.com returned HTTP 403 to both curl and WebFetch, which matters because Trustpilot is the platform the vendor cites for every rating it publishes, https://www.capterra.com/p/263478/Acorn-Finance/ returned HTTP 403, https://www.softwareadvice.com/construction/acorn-finance-profile/ returned HTTP 403, https://www.getapp.com/finance-accounting-software/a/acorn-finance/ returned HTTP 403, https://www.g2.com/products/acorn-finance/reviews returned HTTP 403, https://www.trustradius.com/products/acorn-finance/reviews returned HTTP 403, https://www.bbb.org/us/ca/sacramento/profile/financial-services/acorn-finance-1156-90060258 returned HTTP 403, so the A+ accreditation claim is second-hand from Finder, https://www.consumeraffairs.com/finance/acorn-finance.html returned HTTP 403 and https://www.glassdoor.com/Overview/Working-at-Acorn-Finance returned HTTP 403 refused automated retrieval for Acorn Finance. Where their scores appear in third-party roundups we have left them out rather than pass on a number we could not open.
What that leaves untested: the Contractor Portal itself at https://portal.acornfinance.com/ and https://your.acornfinance.com/app, which require a contractor account. And everything above is 15 vendor pages and a review corpus, which is documentary rather than hands-on.
What Acorn Finance users say
Please avoid this company! They exist to merely collect your private information and sell it to other companies. they have no intention of providing a lending market place for you to shop for the best rates! File a consumer fraud complaint with your local ************************* More complaints = better chance of a lawsuit against this company or at least banned from conducting any kind of business within your respective state! Too bad they don't offer a negative star rating!
I am having work done and in the proposal there was a link to offer financing. I clicked on the link, Acorn asked a couple of questions on how much I was looking for and for what purpose. I answered the questions and then get a call saying I had been approved. After looking over the agreement, the interest rate seemed too high for my liking, I declined the offer and then was told I was eligible for a Line of Credit. I asked for that information to review. Before I could look at the agreement, it asked me to select how much I was planning on drawing out initially on the amount approved and the terms. Never did I get a chance to preview the agreement before selecting the drawn amount. Mind you, I had "already been approved" for a certain amount. I was uncomfortable in moving forward, declined that offer. I have sense received a declination email from another company stating I applied with them, of which I had not.I received two letters in the mail from yet another company saying I was declined for the application I submitted, of which I had not applied for. I found out that Acorn works with a company called ******** and they source lenders to get offers. I was completely surprised and very much unaware that multiple companies would be reviewing my information and pulling my credit. This goes against the Fair Credit Reporting Act. Their actions of obtaining access to my credit was without cause or permission.
Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company.
Acorn did a great job. The Lender with the best rate was suspect. I could not find a phone number anywhere to contact them. I had to go with a higher rate with a reputable company.
The process was quick and I had several offers. I was able to get my loan from one of their partners and so far I am very happy. The interest rates are high.
Easiest loan I have obtained. Excellent customer service. Applied on Friday and had money in the bank on Tuesday morning. Better interest rates than our credit union.
Great job, very easy to do and understand. It took a little longer to receive in my bank then I thought it would.
Applying for financing on Acorn was quick and easy. You can see your options without a hard credit pull and then decide what option works best for you. The only knock is that there are additional loan options and that isn't clear initially. Once I realized that each lender had multiple options I was able to customize the loan to what worked best for me. Highly recommend if you are looking for financing and want multiple options.
Offering financing has made projects more affordable for customers and increased our average job size. Acorn Finance has also helped us get new business and keep existing customers.
We make customers aware of financing through our website. Offering financing has given us a competitive advantage, and our overall experience with Acorn Finance has been good, including their customer service.
This sounds kind of like a combination of everyone else we’ve kind of looked into and taken the best of all of them.
Frequently asked questions
What does Acorn Finance cost a contractor?
Nothing, and the vendor is unusually direct about it. The contractors page states that offering financing is free with no setup costs and no monthly fees, and that the lending partners pay Acorn Finance when loans are originated. The licences page repeats the same thing to consumers, saying Acorn Finance will not charge or seek fees of any kind and receives its fees from lenders. And there's no seat charge, no platform fee and no dealer fee. But the cost sits in the interest rate your customer pays.
Who pays the contractor, the lender or the homeowner?
The homeowner. This is the single most important structural fact about the product and it's what makes the zero fee possible. The lender funds your customer, your customer pays you, and the vendor puts that at one to two business days after project approval. But merchant-funded platforms such as Wisetack and Momnt pay the service provider directly and charge a merchant fee for doing it. And Acorn Finance does neither.
Can my salesperson fill out the application with the customer?
No, and this is a contract term rather than a suggestion. The Dealer Agreement states that the dealer will not complete a consumer loan application for the consumer, including entering consumer data into the online form, and that all applications must be completed by the consumer. And the same clause bans predicting whether a lender will approve someone and bans telling customers that Acorn Finance shows every option available.
What will I be able to see about my customer's loan?
Three facts and nothing more. The Dealer Agreement limits Loan Offer Information to whether an unidentified party made an offer, whether an unidentified party made a loan, and whether Acorn Finance could not find anyone to offer at all. No amount, no rate, no term and no lender name. So if you want to know what your customer was quoted, you have to ask your customer.
How much can a homeowner borrow and at what rate?
The panel writes loans from $1,000 to $100,000. The vendor's FAQ names roughly 560 as the minimum credit score its lenders consider, and its own illustrative example on the partner page uses an 8.94% interest rate on $10,000 over 84 payments of $161, with rates stated as of 14 June 2026. But Finder's June 2026 review puts the realistic band at 6.99% to 35.99% APR. And the FAQ also warns that some lenders charge an origination fee of 1 to 6 percent on loans under $40,000.
How long is the contract and how do I get out?
The Dealer Agreement starts the day you tick the box on the online application, renews automatically after one year, and either side can terminate without cause on 30 days' notice. There's no exit fee, because there's nothing being billed. But what survives is the arbitration agreement, the confidentiality obligations and the indemnity, so leaving doesn't unwind the legal exposure.
How trustworthy are the review scores?
Treat them carefully. The Acorn Finance homepage carries three different Trustpilot figures at once: text reading 4.3 stars out of 5 with 1,200+ reviews, a widget reading 4.7 out of 5 based on 1299 reviews, and a star image whose filename is trustpilot-4.5-stars.png. And independent sites are thinner than they look. Trustindex shows 4.4 from 18 reviews and ComplaintsBoard shows 4.6 from 14, and several review texts appear on both sites word for word under different reviewer names, which means they're one pool and not two.
Freshness
How we keep this page current
Three dates govern this review, and they carry different meanings. The initial source sweep is dated August 7, 2026; when only part of the evidence set is recaptured later, that later date is stated beside the refreshed claim. We last revised the page on August 7, 2026. And the user reviews we quote were posted over roughly the last 24 months, so their individual dates remain part of the evidence instead of being overwritten by a later pricing update.
We revise the page when Acorn Finance changes a published price or a contract term, when a rating we cite moves by more than a few tenths, or when the vendor ships something big enough to change the verdict. We never bump the date just to look fresh, because Google treats that as manipulation and so do we. If a figure here reads as stale by the time you land on it, treat it as a floor and check the vendor's own page. We linked it at every number for exactly that reason.
Sourcing
How this review was researched
Every figure on this page traces to a captured source linked inline where it appears. The initial sweep is dated August 7, 2026; any later, partial recapture is dated at the claim rather than relabelling the whole evidence set. Ratings come from Capterra, GetApp, Software Advice and the Apple App Store. Note that Capterra, GetApp and Software Advice share one Gartner Digital Markets review pool, so an identical score across all three is a single sample rather than three corroborating ones, and this page treats it that way. G2, TrustRadius and Trustpilot block automated access, so where their numbers appear they are labelled as reported rather than verified. No claim here is sourced from Reddit or from a contractor Facebook group, because neither could be retrieved and quoting them would mean inventing attribution. Pricing marked as reported comes from third-party roundups, never from Fervor. Fervor's own findings come from the Contractor CRO Index 2026.
About
About Fervor Studio
Fervor Studio is a conversion rate optimization (CRO) and web design studio for home services contractors across North America, based in Cochrane, Alberta. Fervor does not sell field service management software and is not an alternative to Acorn Finance. It publishes the Contractor CRO Index, a public benchmark measuring contractor website conversion potential using reproducible, open-source methods such as axe-core and Google Lighthouse. Fervor Studio is operated by Fervor Group Inc.
 Aug 2, 2026
Tech Stack
Best Plumbing Software in 2026: Ten Ranked Across Four Classes
A plumbing company’s work runs through four classes of software that do not substitute for each other, and it only buys two of them. Ten products, each with a published price or an explicit statement that the vendor publishes none.
Read Article Jul 31, 2026
Tech Stack
NiceJob vs Birdeye 2026: Pricing, Contracts and Review Gating
One of these vendors puts its price on the page and its cancellation terms in writing. The other puts a form in front of both, and the complaint record is where its contract length shows up.
Read Article Jul 31, 2026
Tech Stack
Podium vs Birdeye 2026: Pricing, Contracts and Review Gating
Only one of these two will tell you what it costs before a sales call, and even that number carries a carve-out aimed squarely at trade contractors.
Read Article Jul 31, 2026
Tech Stack
Best Electrical Contractor Software 2026: 11 Ranked and Priced
An electrical contracting business makes two software purchases that do not substitute for each other, and every roundup answering this query covers only one of them. Eleven platforms, with a published price or an explicit statement that the vendor publishes none.
Read Article Jul 31, 2026
Tech Stack
Best HVAC Software in 2026: Eleven Ranked Across Three Classes
An HVAC contracting business buys across three classes of software that do not substitute for each other, and every roundup answering this query covers only one of them. Eleven products, each with a published price or an explicit statement that the vendor publishes none.
Read Article Jul 30, 2026
Tech Stack
AccuLynx Pricing 2026: The Real Cost of a Quote-Gated Plan
One published figure, two blank plan cards, and a contract that says things the pricing page does not. A line-by-line breakdown of what AccuLynx really bills.
Read Article Jul 30, 2026
Tech Stack
Houzz Pro Canada Review 2026: Pricing and Alternatives
Houzz Pro serves different pricing renderings. What Canadian buyers see, how GST/HST and payments work, what Custom gates, and what the annual contract commits you to.
Read Article Jul 30, 2026
Tech Stack
JobNimbus Pricing in 2026: What the Quote Does Not Cover
JobNimbus prints no figure on any of its four plans. So the only rate you can read before a sales call is the payments meter, and it is the biggest line on the bill.
Read Article Jul 30, 2026
Tech Stack
JobNimbus Review 2026: Pricing, Pros, Cons and Alternatives
JobNimbus rates 4.6 on Capterra and orders material straight from ABC Supply and SRS. But it publishes no price, and its supplement route carries a note.
Read Article Jul 30, 2026
Tech Stack
BuildOps Review 2026: Pricing, Contract Terms and Alternatives
BuildOps runs commercial service and projects on one platform, and publishes no pricing at all. The billing unit, the 30-day data-export window, and who it suits.
Read Article Jul 30, 2026
Tech Stack
FieldPulse Review 2026: Pricing, Pros, Cons and Alternatives
FieldPulse rates 4.6 on Capterra and is the platform contractors name when they leave a bigger system. But it publishes no price, and the contract runs a year.
Read Article Jul 30, 2026
Tech Stack
Service Fusion Review 2026: Pricing, Contract and Alternatives
Service Fusion bills flat per company with unlimited users, which is the best structural deal in field service software. The published plans, the contract behind the no-contract line, and the app score every other review gets wrong.
Read Article Jul 30, 2026
Tech Stack
Knowify Review 2026: Pricing, Job Costing and Alternatives
Knowify rates 4.5 on Capterra and its weakest sub-score is features. What the $99 Core plan withholds, which way the QuickBooks sync really runs, and who should not buy it.
Read Article Jul 29, 2026
Tech Stack
AccuLynx Review 2026: Pricing, Tier Gating, Alternatives
AccuLynx rates 4.6 across 846 reviews and now publishes an entry price. What that price omits, which tier holds the insurance workflow, and who should skip it.
Read Article Jul 29, 2026
Tech Stack
Unitel Voice Review 2026: Pricing, Features and Alternatives
Unitel Voice rates 4.6 on Capterra and gives a one-truck shop a business number for $9.99 a month. The published plans, the cost per call, and what it won't do.
Read Article Jul 29, 2026
Tech Stack
NiceJob vs Podium 2026: Pricing, Contracts and Review Gating
Both vendors print a price, at very different scale and in different currencies. The gap that matters is what Podium will not print: the billing unit, and whether a trade shop gets the number on the page.
Read Article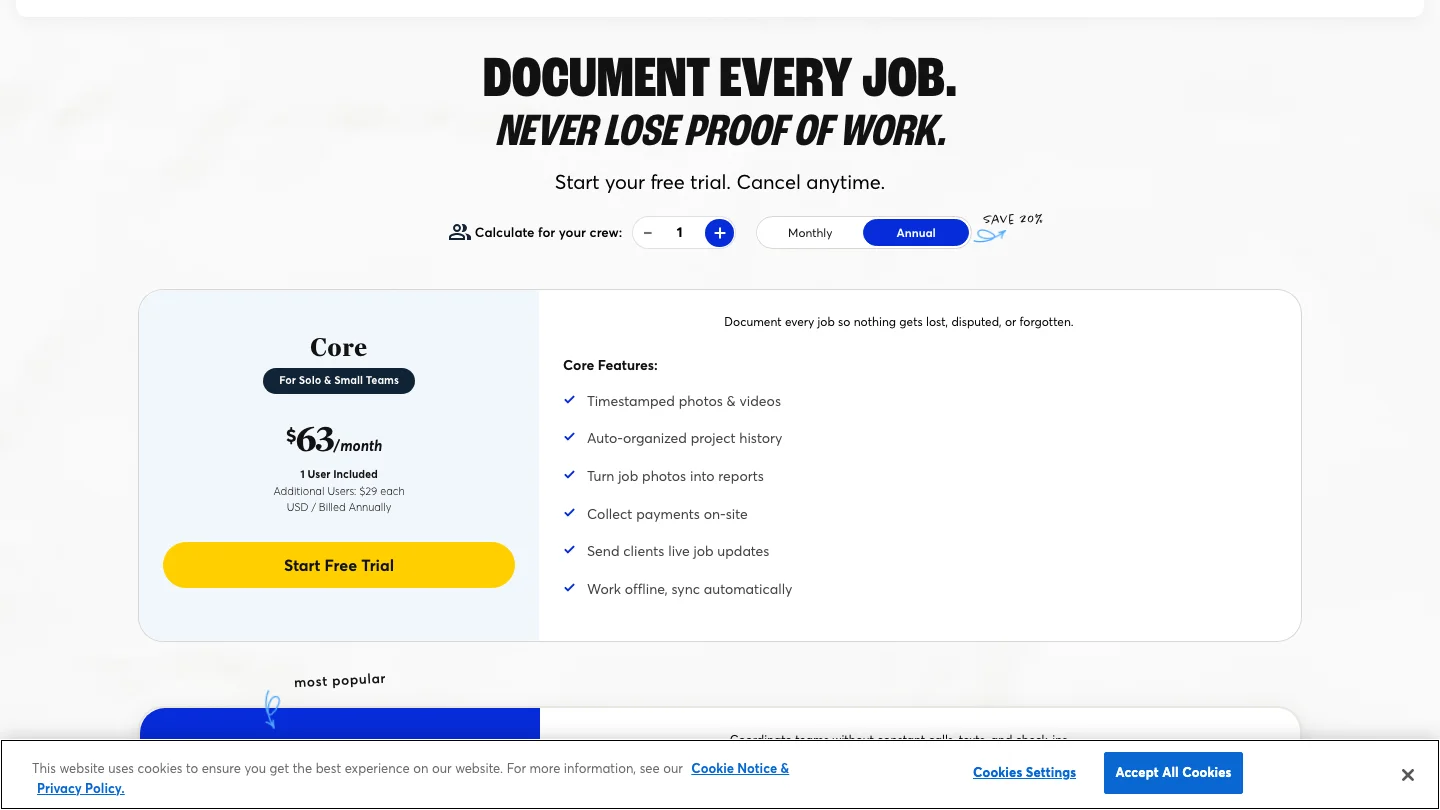 Jul 28, 2026
Tech Stack
CompanyCam Review 2026: Pricing, Pros, Cons and Alternatives
Every page ranking for CompanyCam still quotes a per-user price the vendor no longer charges. Here are the real plans, the seat math, and who should skip it.
Read Article Jul 28, 2026
Tech Stack
NiceJob Review 2026: Pricing, Pros, Cons and Alternatives
NiceJob rates 4.9 on Capterra and refuses to gate negative reviews. Real plan pricing, the active-customer threshold nobody publishes, and who should skip it.
Read Article Jul 27, 2026
Tech Stack
Buildertrend Review 2026: Pricing, Limits and Alternatives
Buildertrend rates 4.5 across 2,486 Capterra reviews and quotes against your revenue rather than your seat count. The workflows, the export problem, the alternatives.
Read Article Jul 27, 2026
Tech Stack
CallRail Review 2026: Pricing, Pros, Cons and Alternatives
CallRail rates 4.5 on Capterra, and its tracking numbers port out free. But the two usage rates that decide your real bill are the two it does not print.
Read Article Jul 27, 2026
Tech Stack
Roofr Review 2026: Pricing, Pros, Cons and Alternatives
Roofr rates 4.6 on Capterra and sells $13 measurement reports against a market charging triple. But it will not import a report from anywhere else.
Read Article Jul 25, 2026
Tech Stack
Housecall Pro Review 2026: Pricing, Pros, Cons, Alternatives
Housecall Pro has the shortest learning curve in the category and the widest review spread. Real pricing, the Instapay math, and the migration trap to plan around.
Read Article Jul 24, 2026
Tech Stack
Jobber Review 2026: Pricing, Pros, Cons and Alternatives
Jobber rates 4.6 on Capterra with the best mobile app in the category. Real plan pricing, the feature gating that changes your entry price, and who it suits.
Read Article Jul 23, 2026
Tech Stack
ServiceTitan Review 2026: Pricing, Pros, Cons, Alternatives
ServiceTitan rates 4.3 on Capterra but its weakest score is value for money. Real reported pricing, the 12-month contract, the exit fees, and who it actually suits.
Read Article Jun 3, 2026
Tech Stack
HVAC Online Scheduling: The 43% Losing After-Hours Bookings
HVAC leads every trade on online booking at just 56.7%, which still leaves 43% of sites forcing an after-hours customer to wait for a business-hours phone call.
Read Article